


September 21, 2026 marks a remarkable milestone for Vietnam's capital market when FTSE Russell's reclassification of Vietnam from a marginal market to a secondary emerging market officially takes effect[1]. But upgrading does not mean that the reform process is complete. On the contrary, when entering the emerging market group, the more difficult question is: how does the Vietnamese stock market really operate according to the standards of an emerging market?
The requirement for foreign investors to have sufficient funds before placing a buy order used to be one of the significant barriers to access to the Vietnamese market.
This question is even more noteworthy when the Securities Law is continuing to be amended. The draft, which was considered by the National Assembly Standing Committee on September 3, 2026, is expected to amend 23 articles, add a new article, with many contents on simplifying procedures, electronic transactions and controlled testing mechanisms[2].
The new context also sets a higher measure for this amendment of the law: not only removing existing obstacles, but also preparing a legal framework commensurate with the new position of the market.
Non-prefunding[3] is just the beginning
The requirement for foreign investors to have sufficient funds before placing a buy order used to be one of the significant barriers to access to the Vietnamese market. With international investment funds trading simultaneously in multiple markets, having to transfer funds upfront not only increases the cost of capital, but also creates additional foreign exchange risk and operating costs.
The implementation of the non-prefunding mechanism is therefore an important change. However, removing the requirement to have enough money before the transaction solves the problem of whether investors can trade smoothly or not, and does not fully solve the question of how the risk of the transaction will be allocated and handled.
This is why the introduction of the central clearing partner (CCP) mechanism into substantive operation becomes the next reform step. When the CCP is substantively operational, the law must simultaneously address the issues of margin, collateral, risk management, failed transactions, and the case of insolvency of members.
In other words, non-prefunding removes a barrier for capital inflows; while CCP creates a foundation for capital flows to be able to transact on a large scale without proportionately increasing systemic risks. This is a step from reform to upgrade to post-upgrade market infrastructure reform.
"Foreign room": the problem is not just a percentage
The second bottleneck is much more difficult to solve: foreign ownership limits.
A market can be upgraded but if foreign investors can't buy enough stocks they need, access is still limited in practice.
The problem lies in the fact that the foreign ownership limit in Vietnam is not only governed by the Securities Law. It is contained in a series of regulations related to investment, banking and conditional business lines, as well as specific limits that apply to each enterprise. Therefore, this is not a bottleneck that can be removed by a single provision in the Securities Law.
After the upgrade, Vietnam needs to shift its approach from the question "How much is the maximum foreign investor allowed to own? " to a broader question: "In what areas is the restriction of ownership really necessary, and to what extent is it reasonable?" This requires a synchronous review of the legal system instead of just adjusting the securities law alone.
If this problem is not addressed, the size of the market's capitalization may continue to increase, but the amount of securities that can actually absorb the capital flows of international institutions is still limited.
IPOs and listings still need a shorter path
An emerging market cannot rely solely on liquidity or stock prices. It needs to constantly add listed businesses with scale, good governance, and a large enough ratio of freely transferable shares.
Meanwhile, IPO and listing in Vietnam have not really become a seamless process. Businesses can complete the offering, but investors still have to wait longer before securities are traded on the centralized market. This gap is not just a procedural issue. When investors have invested capital but securities cannot be traded smoothly, this period also increases liquidity risks for investors.
The draft amendment to the Securities Law is in the direction of cutting some conditions, documents and procedures. But deeper reform should aim to closely connect the IPO process with listing, rather than just shortening each procedure individually.
A market that wants to become an important capital channel of the economy must simultaneously do two things: protect capital investors and make capital mobilization fast enough and reliable enough for good businesses to choose the stock market instead of continuing to rely mainly on bank credit.
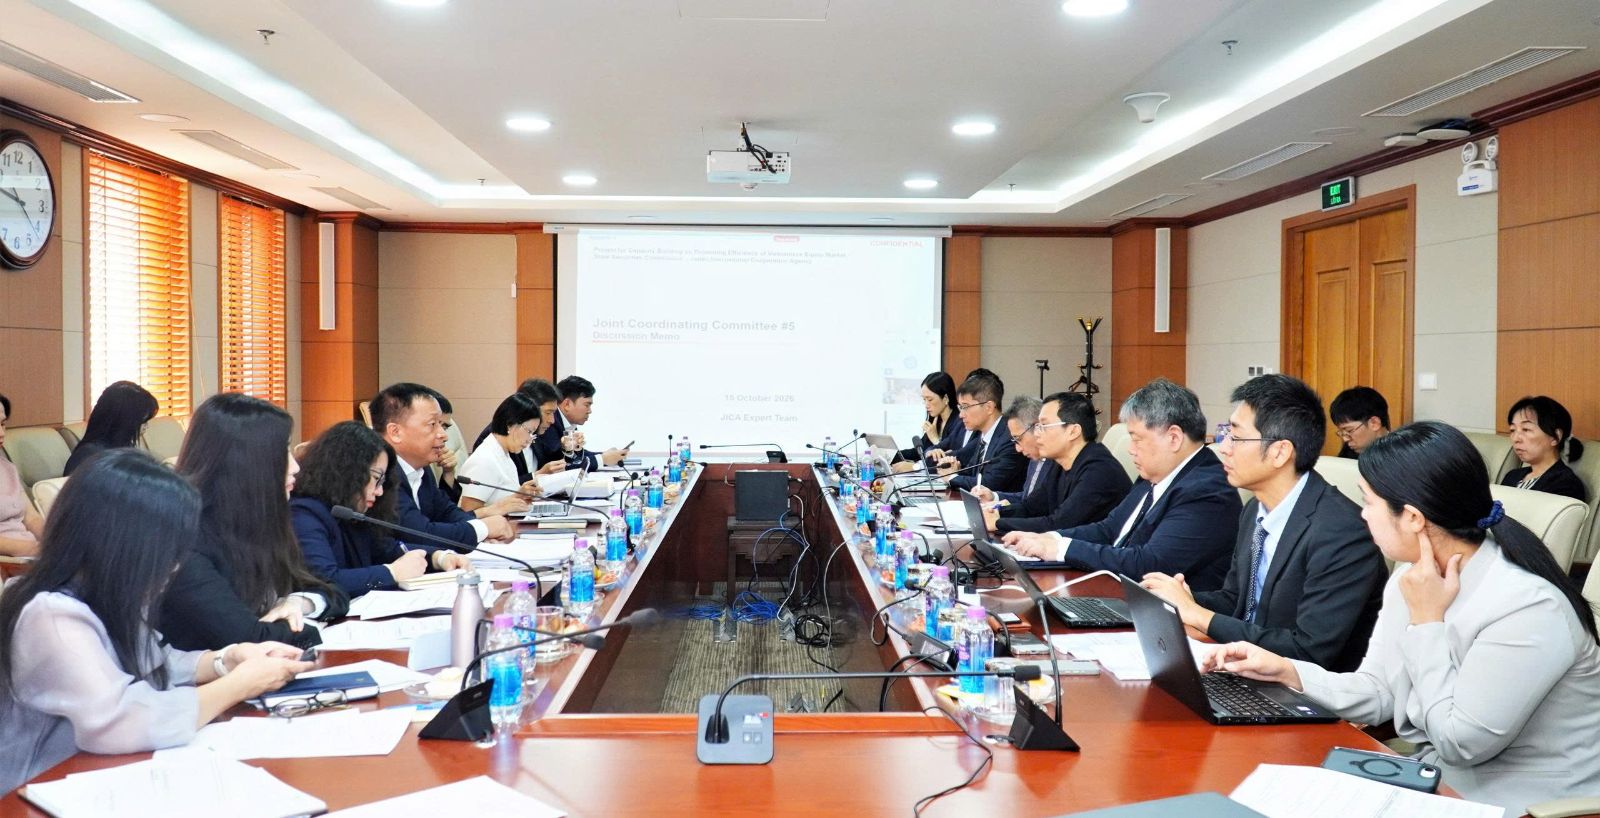
Overview of the working session on the Project “Enhancing Capacity to Promote the Efficiency of Vietnam’s Equity Market”. Source: SSC.
Reducing pre-inspection must be accompanied by increasing post-inspection
Another notable amendment of the Draft Securities Law is to cut business investment conditions and simplify procedures. This is a necessary direction, but reducing pre-inspection cannot mean reducing safety standards.
The important question is therefore not how many more conditions can be removed, but which mechanism will replace the abolished conditions for risk control. As the inspection of the regulator at the input decreases, the responsibility must be shifted more strongly to the issuer, securities companies, auditors, consulting organizations and those responsible for information. At the same time, the ability to detect and handle manipulation, insider trading or disclosure of false information must increase accordingly.
This requires Vietnam to gradually shift from predominantly record-based management to data- and risk-based supervision, in which data from trading, depository – clearing, securities companies, banks and regulatory agencies need to be better connected; at the same time, the ability to identify the ultimate beneficiary owner must also be enhanced to identify relevant accounts and hidden actual interests. But post-inspection is not just about detecting violations. For a market that wants to attract international investors, the quality of information disclosure must also be considered a part of the market infrastructure. Information needs not only to be on time, but also to be reliable enough, accessible and capable of practical use.
Reducing pre-inspection is only really a reform if the post-inspection capacity increases accordingly. Otherwise, the part of the risk that is cut off from the regulator may end up only being passed on to the investor.
Sandbox: what matters is what happens after the test
The draft also lays the foundation for a controlled testing mechanism (sandbox) in the securities sector. This is a necessary step when technology is changing the way investors are identified, advised, distributed securities and managed assets. However, the biggest difficulty of the sandbox does not lie in allowing a new model to be tested, but in the post-test legal path.
The problem is how the successful product will be commercialized, who has the authority to decide, and how investor interests, data, and the responsibilities of the parties will be handled if the test fails.
If these questions remain unaddressed, the sandbox may create space for experimentation but not necessarily a path for innovation to go to market.
After the upgrade, reform must go into substance
Becoming a secondary emerging market is an important achievement. But it is this achievement that changes the reference standard of the reform process.
In the past, the main goal was to remove barriers that prevent Vietnam from meeting the upgrade criteria. From now on, the question must be different: is Vietnam's legal framework competitive enough to compete with other emerging markets?
Upgrade is therefore not the destination of reform, but a change in standards that the Vietnamese market must meet. After the upgrade, the measure of reform is no longer the number of barriers removed, but the quality of market operations: access to capital, risk management, information transparency and the level of investor protection.
If before the upgrade, Vietnam mainly removed barriers for international capital flows to enter, then after the upgrade, Vietnam must build a market that is transparent, efficient and safe enough for capital flows to stay. That is the real test for the process of perfecting the legal framework of the Vietnamese stock market after the upgrade.
Lawyer Nguyen Van Phuc
HM&P Law Firm
[1] https://baochinhphu.vn/chung-khoan-viet-nam-chinh-thuc-gia-nhap-ro-chi-so-toan-cau-ftse-russell-102260918194839151.htm, accessed on 05/10/2026.
[2] https://quochoi.vn/UBTVQH/tintuc/Pages/tin-hoat-dong.aspx?ItemID=2535, accessed on 05/10/2026.
[3] Non-prefunding: is a mechanism that allows foreign institutional investors to place an order to buy shares without having 100% of the funds available in the account at the time of placing the order.


