


In the context that Vietnam's insurance market has entered a period of strong volatility after more than two years of implementation of the Law on Insurance Business 2022, with many high-profile cases related to bancassurance, contract disputes, governance capacity and information transparency requirements, The revision of the legal framework is becoming an urgent need. In particular, as the economy enters a new growth cycle and Vietnam continues to expand its service market in line with international commitments, the insurance industry is forced to upgrade its operating mechanisms to meet expectations for efficiency, safety and compliance.
The Draft Law amending and supplementing a number of articles of the Law on Insurance Business ("Draft") submitted by the Government to the National Assembly in 2025 clearly reflects this orientation: Reducing business conditions to promote investment, strongly decentralizing to reform procedures, and increasing risk management capacity in the direction of approaching international standards. This is not just a technical review activity, but a step to adjust the strategy, shaping the future of the insurance industry in the next 10 years.
1. Cutting business investment conditions to attract investors
One of the biggest focuses of the Draft is the abolition or simplification of a series of business investment conditions, applicable to many entities participating in the insurance market in Vietnam. Of the total 25 articles amended, 7 articles focus on this group of policies.
First, abolishing the foreign requirement for certification of "no serious violations"
According to current regulations, a foreign organization wishing to establish an insurance enterprise in Vietnam must obtain a written certification from the competent authority in the host country that the enterprise has not committed serious violations within the last three years[1]. This regulation is considered to have a reasonable goal, preventing organizations with moral risks or bad precedents from entering the Vietnamese market.
However, in practical terms, this is a "technical bottleneck" that is difficult to meet, because many countries do not maintain the mechanism for issuing such certificates. As a result, many potential investors are unable to complete their profiles, even though they meet financial and governance standards.
The Draft abolishment of this requirement is in line with the policy of Resolution 198/2025/QH15 on removing barriers to market access, increasing the level of competition and improving Vietnam's attractiveness to large insurance groups in the world.
Second, completely eliminate the condition "before officially operating"
Another important change is the abolition of all pre-operating conditions such as: Internal management regulations, deposit requirements, standards of facilities, conditions on professional personnel,... These conditions used to be a significant barrier for new businesses to enter the market when they had to complete a large amount of procedures before being allowed to operate.
Instead of "pre-audit", the Draft moves to a post-audit mechanism, focusing on internal control, internal audit, risk management (Section 3 Chapter III) and escrow regulations (Article 96).
This model creates space for businesses to be more proactive, reduce the cost of entering the market, but still ensure that the State maintains the ability to supervise during operation.
Third, eliminate the general conditions and standards of managers
According to the Draft, individuals appointed to key management positions (Clauses 2, 3, 4 of Article 81) will no longer be excluded from the appointment list just because they have been administratively sanctioned in the field of insurance, disciplined in the form of dismissal, etc. or have been prosecuted.
The reason for this change is to relieve difficulties in human resources of enterprises, in line with the context of domestic human resource training that has not really met the needs of the insurance market.
However, this relaxation still requires careful supervision in the future, in order to avoid risks to the quality of insurance corporate governance.
Fourth, reduce conditions for insurance brokerage enterprises
In addition to eliminating the requirement for confirmation of "no serious violations", the Draft also eliminates compliance obligations related to the form of organization and operation and the draft charter. This helps brokerage activities, which are an important link in the supply chain of insurance products, to operate more flexibly and quickly.
2. Unifying the conditions for establishing an enterprise under the Law on Enterprises
A notable reform is the addition of Clauses 3 and 4 of Article 3 of the Draft, thereby removing duplicate regulations that have appeared in many documents and synchronizing the reference system to the Law on Enterprises and the Civil Code.
Accordingly, organizations and individuals contributing capital to establish insurance enterprises, reinsurance, insurance brokers, mutual organizations providing microinsurance or foreign branches will apply the conditions under the Law on Enterprises; individuals practicing as insurance agents or providing insurance auxiliary services must meet the civil act capacity according to the Civil Code.
Agreeing on common law conditions increases the transparency of the legal system, reduces the risk of overlap and improves investor predictability.
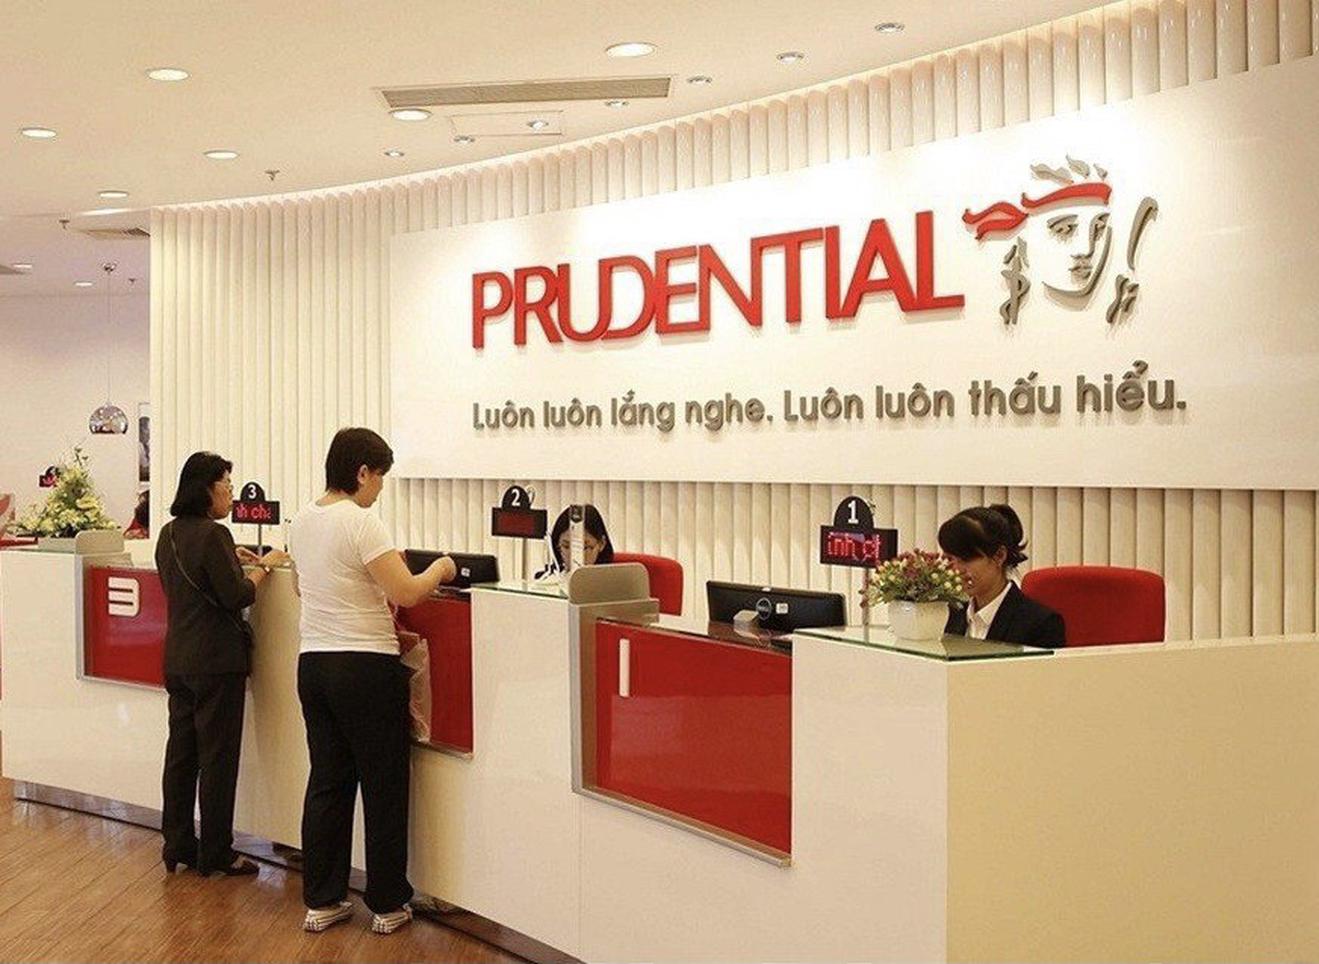
Prudential Vietnam Life Insurance LLC. Source: Thanh Tra
3. Promoting decentralization and decentralization among management agencies
Codifying the guidelines of Resolution 66-NQ/TW, the Draft continues to clearly demonstrate the goal of reducing the workload for central ministries and increasing the role of local governments.
Firstly, transferring the authority to receive notices of insurance branches to the provincial-level business registration authority
According to Clause 3a, Article 74 of the Draft, when an insurer, reinsurance enterprise or foreign branch opens, terminates, changes its name, or changes the location of its branch, it will only need to notify the provincial business registration authority within 10 days from the date of the change.
Previously, this procedure had to be sent to the Ministry of Finance and often took a long time to process. This decentralization is expected to significantly shorten the time to complete procedures and reduce administrative pressure on the central management agency.
Second, move from "registration – waiting for approval" to "just notify"
Clause 3b, Article 87 of the Draft stipulates that non-life insurers only need to notify in writing when applying or changing the premium calculation method instead of having to register and wait for the Ministry of Finance's approval as before.
Similarly, enterprises only need to notify the principle of equity, without having to carry out official registration procedures.
The reason given by the Ministry of Finance is that the characteristics of non-life insurance products are short-term and have a reinsurance rate of up to 60-70%, and the level of systemic risk is lower.
Third, some other important procedural reforms
In addition, the Draft also proposes to remove the requirement that enterprises must notify the Ministry of Finance after disclosing information; clarify the scope of operation of insurance agents; extend the time limit for conversion of insurance agent certificates.
These adjustments have the effect of reducing compliance costs and avoiding "paper stacking".
4. Enhancing financial security and risk management to move to a risk-based capital (RBC) model
One of the strategic changes of Vietnam's insurance industry is to build a risk-based capital model (RBC), which is being widely applied in advanced markets such as Singapore, Japan, and South Korea. RBC is a model that assesses the capital requirements of businesses based on market risk, operational risk, liquidity risk, governance risk and information transparency. RBC's advantages are increasing the resilience of businesses to market fluctuations, raising internal governance standards and limiting the risk of insolvency, one of the biggest concerns of regulators. The Law on Insurance Business 2022 has approached this model, but only at the level of "laying the foundation".
The Ministry of Finance is building a database and monitoring system to implement RBC in the period of 2026 – 2030. It is expected that from 2028 to 2030, insurers will have to officially apply the RBC model. This period is considered a "golden period" for businesses to test, adjust policies, restructure products and upgrade management technology systems.
Switching to RBC isn't just about changing the capitalization formula. It requires a team of high-quality risk management and actuarial experts, a complete and compatible data system, a rigorous internal audit process, and an IT infrastructure that meets the risk analysis model.
This will be a big challenge for small and medium-sized enterprises, but it is an inevitable condition for the healthy development of the market.
The Draft Law amending and supplementing a number of articles of the Law on Insurance Business 2022 shows strong efforts in creating a transparent, open and attractive investment environment through reducing business conditions and simplifying procedures; ensure more effective state management by rational decentralization and increase the autonomy of enterprises and improve financial safety and risk management with the roadmap to apply the RBC model, in line with international standards. With the orientation of shifting from the "pre-inspection" to "post-inspection" mechanism, focusing on governance and compliance, the Draft not only helps businesses reduce operating costs, but also contributes to increasing the transparency and competitiveness of Vietnam's insurance market. When approved by the National Assembly, this will be an important step forward, creating a legal foundation for the insurance industry to develop sustainably, meeting the requirements of deep integration in the new period.
Lawyer Nguyen Nhat Duong - Nguyen Viet Hung
HM&P Law Firm
Read more: Sửa đổi Luật Kinh doanh bảo hiểm 2022: Hướng tới một thị trường minh bạch, cạnh tranh và an toàn hơn
[1] Point b, Clause 1, Article 65 of the Law on Insurance Business 2022.


