


The certificate of science and technology enterprise is the basis for enterprises to enjoy the State's preferential policies and investment support, and at the same time be allowed to carry out research, development and innovation activities in accordance with law.
According to Decree No. 268/2025/ND-CP, enterprises will be granted a Certificate when they fully meet the general conditions and specific conditions corresponding to the size of the enterprise, which are determined according to the regulations on supporting small and medium-sized enterprises. The Decree also specifies the mechanism for encouraging, recognizing and supporting organizations and individuals to participate in the national innovation ecosystem.
The following article will summarize the conditions, order and procedures for enterprises to be granted a science and technology enterprise certificate according to the new regulations.
1. What are the benefits of a science and technology enterprise certificate for businesses?
Enterprises that carry out research, development, transfer and innovation activities, have the capacity to absorb and master technology and bring economic, social and environmental efficiency may be granted a certificate of science and technology enterprise by a competent state management agency if they meet the conditions specified in Article 49 of Decree 268/2025/ ND-CP.[1]
With this Certificate, enterprises can carry out scientific, technological and innovation activities, and at the same time enjoy the State's preferential policies and supports in accordance with the law on investment, bidding, taxation, credit, land, science, technology and innovation and other legal provisions.[2] In addition, when a new product is additionally granted to the Certificate of Science and Technology Enterprise, the enterprise continues to enjoy preferential and support policies as for the first time, counting from the date it is added to the Certificate. The above incentives are specified as follows:
1.1. Priority is given to leasing land and infrastructure in industrial parks, export processing zones, economic zones, hi-tech parks, high-tech agricultural zones, and concentrated digital technology parks
Science and technology enterprises that use land for the construction of the following works shall be exempt from land rents for the whole lease term:[3]
- Laboratory;
- Technology incubators and science and technology enterprise incubators;
- Experimental facilities;
- Trial production facilities.
Facilities and infrastructure used to support scientific research, technological development and innovation of science and technology enterprises are also eligible for exemption or reduction of land use levy and land rent.[4]
In addition, houses and land of science and technology enterprises that register land use rights and house ownership are exempt from registration fees.[5]
1.2. Prioritize the use of research and development equipment at shared laboratories, incubators and innovation centers
The Innovation Center meets the statutory criteria on technical infrastructure to meet the requirements of implementing innovation, supporting innovation and creative start-ups in accordance with sectors, fields and localities such as:[6]
- There are working and connected spaces such as: Office; seminar rooms; consultation and connection space; space for demonstration and display of technology products;
- There is digital and data infrastructure such as: Internet; expert and technology databases;
- There are shared utilities and services.
1.3. Supported with information, communication and trade promotion
The state budget is entitled to support the operation of science and technology enterprises, including:[7]
- Expenses for trade promotion support for science and technology enterprises: expenses for organizing conferences, seminars, trade delegations and trade promotion events at home and abroad, per diem allowances for business trippers at home and abroad; expenses for organizing conferences, international conferences; welcoming foreign delegations to Vietnam to participate in fairs, exhibitions, market surveys and transactions with Vietnamese enterprises; expenses for investigation, survey to find out information, research and assess demand for products, commodity lines and markets; expenses for hiring consultants to develop products, improve product quality, export products, penetrate foreign markets; experts in market and product research, consultancy and evaluation; expenses for propagation, promotion, provision of information, development and distribution of publications in service of trade promotion programs;
- Expenses for supporting the operation of science and technology enterprises: support for the use of technical establishments, incubators and co-working areas; support for consultancy contracts for search, selection, decoding and transfer of technology; support for training and intensive coaching; support for training, fostering at home and abroad on the transfer of technological know-how, receiving, operating and mastering technology, productivity, quality and intellectual property; technology management, technology administration and new technology updates.
1.4. Corporate income tax incentives
Science and technology enterprises under the provisions of the Law on Science, Technology and Innovation belong to the group of enterprises with industries and trades eligible for corporate income tax incentives according to Point e, Clause 2, Article 12 of the Law on Corporate Income Tax 2025. Specifically, the income of science and technology enterprises is subject to a preferential tax rate of 10% for 15 years[8], and at the same time is exempt from tax for up to 04 years and reduced by 50% of the payable tax amount for a maximum of 09 years.[9]
The tax exemption or reduction period is counted from the year of issuance of the Certificate; in case there is no income in the year of issuance of the Certificate, the tax exemption or reduction period shall be counted from the first year of income, if in the first 03 years from the year of issuance of the Certificate, the tax exemption period, tax reduction from the 4th year.[10]
1.5. Personal income tax incentives
Incomes from salaries and wages from the performance of scientific, technological and innovation tasks of researchers at science and technology enterprises are incomes not subject to personal income tax, specifically including:[11]
- Incomes from salaries and wages from the performance of scientific, technological and innovation tasks;
- Income from copyright of science, technology and innovation tasks when the results of tasks are commercialized in accordance with the law on science, technology and innovation and the law on intellectual property.
1.6. Import tax incentives
Raw materials, supplies and components imported for production and research of science and technology enterprises shall be exempt from import tax for a period of 05 years from the date of commencement of research and production[12].
Science and technology enterprises are entitled to various preferential policies and support measures. Source: Government News
2. Overview of conditions for issuance of science and technology certificates
2.1. General conditions[13]
- Established and operating under the Law on Enterprises
- Creating scientific, technological and innovative products from one of the results of scientific research, technological development and innovation that are lawfully owned or used, including:
- Patent; useful solutions; industrial designs; design of the layout of semiconductor integrated circuits protected in Vietnam;
- Computer programs that have been granted copyright registration certificates;
- New breeds of livestock; new plant varieties; new aquatic breeds; new forestry tree varieties; technical advances that have been protected or recognized;
- The results of scientific research, technological development and innovation have been accepted or certified and recognized in accordance with law;
- The technology transferred under the technology transfer contract has been registered in accordance with the law on technology transfer.
2.2. Specific conditions
Enterprises can base on Article 4 of the Law on Support for Small and Medium Enterprises 2017 and Article 5 of Decree 80/2021/ND-CP when determining the size of their enterprises:
i. Small and medium-sized enterprises include micro-enterprises, small enterprises and medium-sized enterprises, with an average annual number of employees participating in social insurance of not more than 200 people and meeting one of the following two criteria:
- The total capital does not exceed 100 billion VND;
- The total revenue of the preceding year does not exceed VND 300 billion.
ii. Micro-enterprises, small enterprises and medium-sized enterprises are defined by the fields of agriculture, forestry and fisheries; industry and construction; trade and services. Details of this article are specified in Chapter II of the Government's Decree No. 80/2021/ND-CP dated August 26, 2021 detailing and guiding the implementation of a number of articles of the Law on Support for Small and Medium Enterprises.
iii. Large enterprises: there are currently no specific regulations on which enterprises are identified as large-scale enterprises, but it can be based on the exclusion of criteria for small and medium-sized enterprises and micro-enterprises to determine large enterprises by sector.
Based on the size of the above-mentioned enterprise, the enterprise can determine the conditions for being granted a science and technology enterprise certificate, specifically as follows:
|
Condition |
Large enterprises[14] |
Medium-sized enterprises[15] |
Small and micro businesses[16] |
|
Conditions on total expenditures for scientific research and technological development activities |
|
|
|
|
Human resource conditions |
Having a research and development department with at least 10 human resources with university degrees or higher, of which at least 05 human resources are Vietnamese |
There is a research and development department with at least 05 human resources with a university degree or higher, including Vietnamese human resources |
|
|
Conditions on scientific, technological and innovative products |
|
|
There is at least 01 scientific, technological and innovative product being commercialized |
3. Overview of procedures for applying for science and technology certificates at competent agencies
|
No |
Category |
Content |
|
1 |
Dossier-receiving and processing agencies |
Provincial People's Committees (Department of Science and Technology) |
|
2 |
How it works |
Submit online through the public service system. |
|
3 |
Profile Components |
The enterprise submits 01 (one) set of dossier including[17]:
|
|
4 |
Fees and charges |
Fees are not applied to this administrative procedure. |
|
5 |
Result |
|
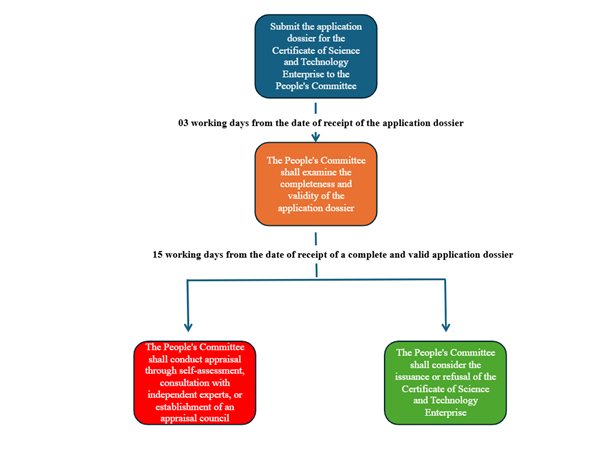
4. The process of applying for a science and technology certificate
The dossier is submitted through the public service system according to regulations[18] and processed in the following order:
5. Validity of science and technology enterprise certificates and cases of revocation or invalidation of science and technology enterprise certificates[19]
Every 03 years from the date of issuance of the Certificate of Science and Technology Enterprise, the Department of Science and Technology shall inspect and assess the observance of statutory conditions to consider the maintenance of the validity of the Certificate of Science and Technology Enterprise.
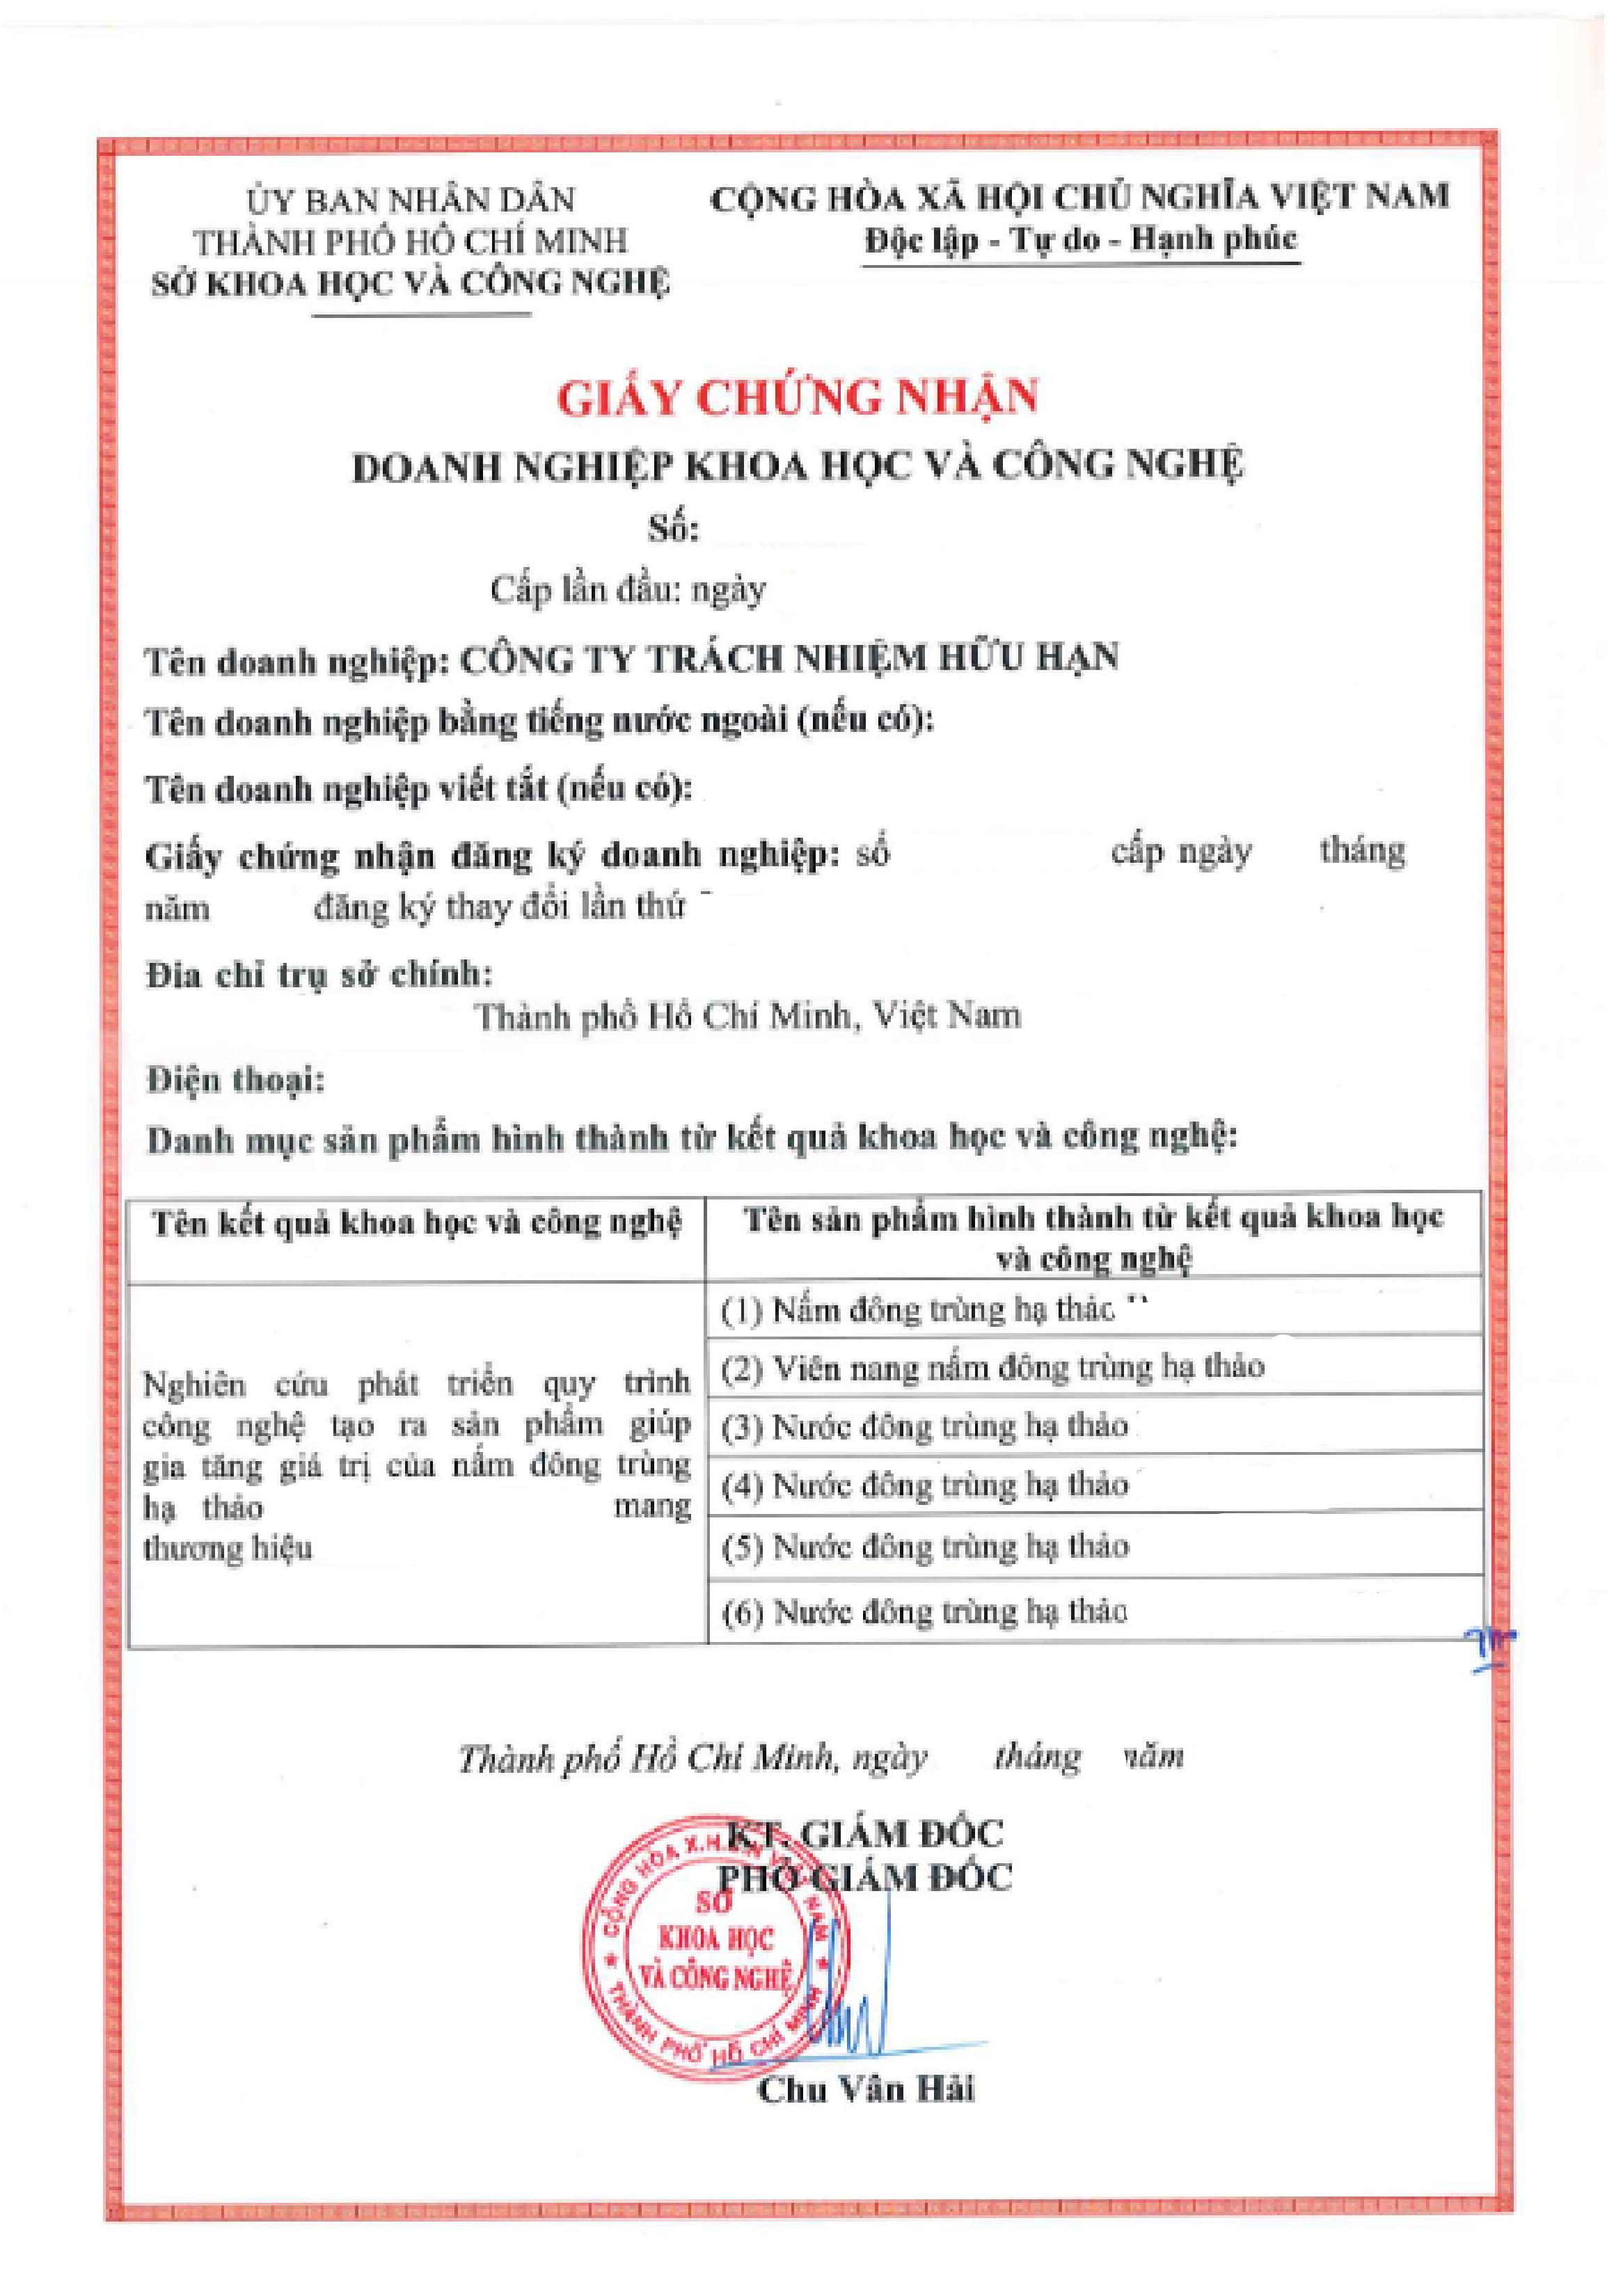
The certificate of science and technology enterprise
The Department of Science and Technology shall notify the enterprise and decide to revoke the certificate of science and technology enterprise in the following cases:
- Science and technology enterprises are dissolved, bankrupt or revoke enterprise registration certificates in accordance with law;
- Science and technology enterprises fail to implement the reporting regime for 03 consecutive years as prescribed;
- Enterprises no longer have the right to legally own or use technologies and results of scientific research, technological development and innovation;
- The enterprise fails to meet the conditions specified in Article 49 of Decree 268/2025/ND-CP for 03 consecutive years.
- In case the certificate of science and technology enterprise is revoked, the enterprise shall no longer be entitled to the State's preferential policies and support for science and technology enterprises.
The Department of Science and Technology shall decide to invalidate the certificate of science and technology enterprise in the following cases:
- Committing acts of infringing upon the ownership or right to use technologies and results of scientific research, technological development and innovation declared in dossiers of application for certification of science and technology enterprises;
- There are acts of forging the contents of the dossier of application for certification of science and technology enterprises.
In case the certificate of science and technology enterprise is invalidated, the enterprise shall have to refund all the State's incentives and supports for science and technology enterprises that have been enjoyed and handled according to the provisions of law.
[1] Clause 1, Article 47, Article 49 of Decree No. 268/2025/ND-CP.
[2] Clause 1, Article 56 of Decree No. 268/2025/ND-CP.
[3] Point đ, Clause 1, Article 5 of Decree No. 230/2025/ND-CP.
[4] Clause 4, Article 71 of the Law on Science, Technology and Innovation 2025.
[5]Clause 30, Article 10 of Decree No. 10/2022/ND-CP.
[6] Clause 3, Article 29 of Decree No. 268/2025/ND-CP.
[7] Point c, Clause 6, Article 6, Point d, Clause 6, Article 6, Point dd, Clause 4, Article 6 of Decree No. 265/2025/ND-CP.
[8] Clause 1, Article 13 of the Law on Corporate Income Tax 2025.
[9] Point a, Clause 1, Article 14 of the Law on Corporate Income Tax 2025.
[10] Clause 4, Article 14 of the Law on Corporate Income Tax 2025.
[11] Clause 3, Article 71 of the Law on Science, Technology and Innovation 2025.
[12] Point c, Clause 21, Article 16 of the Law on Import and Export Taxes 2016 (amended and supplemented by Law No. 90/2025/QH15 dated June 25, 2025).
[13] Clause 1, Article 49 of Decree No. 268/2025/ND-CP.
[14] Clause 2, Article 49 of Decree No. 268/2025/ND-CP.
[15] Clause 3, Article 49 of Decree No. 268/2025/ND-CP.
[16] Clause 4, Article 49 of Decree No. 268/2025/ND-CP.
[17] Clause 2, Article 50 of Decree No. 268/2025/ND-CP.
[18] Article 48, Clause 1, Article 50 of Decree No. 268/2025/ND-CP.
[19] Article 53 of Decree No. 268/2025/ND-CP.


