Guidance on procedures for registration of peer-to-peer lending mechanism for Fintech companies
From July 1, 2025, peer-to-peer lending (P2P Lending) activities in Vietnam have been officially included in the legal framework in Decree 94/2025/ND-CP. This is an important step forward to control risks and protect consumers in the context of strong development of Fintech models. However, to participate in this mechanism, Fintech companies must meet a series of strict conditions and fully carry out registration procedures with the State Bank of Vietnam. The following article will provide specific instructions on the conditions and registration process for participating in the Peer-to-Peer Lending Trial Mechanism that businesses need to pay attention to.

1. Regulations on peer-to-peer lending mechanism
The Government has issued Decree 94/2025/ND-CP to establish a controlled testing mechanism in the banking sector for new products, services and business models applying financial technology ("Fintech solutions"). Among them, the peer-to-peer lending solution – that is, the information technology application model provided by businesses to connect borrowers and lenders, support the conclusion of contracts on a digital platform – is identified as one of the Fintech solutions eligible to participate in the Pilot Mechanism as prescribed in this Decree.
Notably, the Decree also opens up significant opportunities for financial technology companies that are not credit institutions or foreign bank branches but have a license to establish or legally register a business in Vietnam ("Fintech Companies"). These companies are allowed to provide Fintech solutions on their own or coordinate with credit institutions and foreign bank branches to deploy to the market.
However, in order to be able to operate in the field of peer-to-peer lending, Fintech companies must meet strict conditions and criteria as prescribed, and at the same time fully carry out the procedures for registering to participate in the Pilot Mechanism for peer-to-peer lending solutions.
2. Conditions and criteria for participating in the peer-to-peer lending sector for Fintech companies
|
Conditions and criteria
|
Plot
|
|
Conditions for peer-to-peer lending solutions
|
- Having technical and professional contents that current legal regulations have not specifically and clearly guided the implementation and application;
- Be innovative, bring benefits and added value to service users in Vietnam, especially solutions to support and promote the goal of financial universalization;
- It has designed and built a risk management framework, limiting negative impacts on the banking system and banking - monetary - foreign exchange activities; developed a plan on handling and overcoming risks occurring during the testing process; has developed a plan to protect consumer rights;
- The Fintech Company has taken measures to fully review and evaluate the aspects of operation and function, utility, and usefulness;
- It is feasible to be able to supply to the market after completing the testing process.
- Take measures to identify and manage the maximum outstanding debt for a borrower at the peer-to-peer lending solution provided by the borrower, report and exploit instant information about the borrower at the Vietnam National Credit Information Center to ensure compliance with regulations on the maximum outstanding debt for a borrower at the solution peer-to-peer loans provided by the borrower and the maximum outstanding debt for a borrower in all peer-to-peer lending solutions participating in the Pilot Mechanism;
- The disbursement and payment of loans, interest and fees for transactions of customers at peer-to-peer lending solutions must be made through the customer's payment account at a credit institution, foreign bank's branch or the customer's e-wallet at the payment intermediary service provider;
- There are measures to ensure that the contract term between the borrower and the lender using the peer-to-peer lending solution participating in the Pilot Mechanism does not exceed 02 years.
|
|
Conditions for Fintech Companies
|
- Being an enterprise legally established and operating in the territory of Vietnam; not being a foreign-invested enterprise; not in the process of division, separation, consolidation, merger, transformation, dissolution or bankruptcy as prescribed by law;
- The legal representative, General Director (Director) of the Company is a person with Vietnamese nationality; no criminal record; not being sanctioned for administrative violations in the fields of finance, banking and cybersecurity; not concurrently being the owner or manager of an enterprise providing financial services, banking, pawn or multi-level business; not being the owner of wires, surnames, wards or being members of the Board of Directors, members of the Board of Members, members of the Control Board, General Director (Director), Deputy General Director (Deputy Director) and equivalent titles of credit institutions or foreign bank branches, payment intermediary service providers;
- The legal representative, General Director (Director) of the Company must have a university degree or higher in one of the fields of economics, business administration, law, information technology and have at least 02 years of experience as a manager or executive of the organization in the field of finance, banks and are not prohibited by law.
|
|
Standards of human resources, facilities and techniques in Fintech companies
|
Standards on human resources, material foundations and techniques for digital platforms deploying peer-to-peer lending solutions ensure the following minimum requirements:
- Information technology systems and information storage systems must be located in the territory of Vietnam, operate safely and continuously, and backup technical systems are independent of the main system to ensure uninterrupted incidents occur, especially technical incidents, technology.
- The data and information of all customers and related parties must be updated, stored and shared on a highly confidential digital platform, ensuring transparency and publicity between the participating parties but at the same time must keep the information of the participating parties confidential to unrelated parties in accordance with the law.
- Testing and evaluating information technology systems before putting them into operation.
- A team of technical staff with professional qualifications in the field is responsible for ensuring the safe and continuous operation of the system.
|
Note No. 1:
Peer-to-peer lending companies participating in the Pilot Mechanism are responsible for ensuring that all conditions and criteria are maintained during the process of participating in the Pilot Mechanism.

Current status of the Fintech ecosystem. Source: State Bank of Vietnam
3. Overview of procedures for registration to participate in the Peer-to-Peer Lending Trial Mechanism[1]
|
STT
|
Category
|
Plot
|
|
1
|
Receiving agency
|
State Bank of Vietnam
|
|
2
|
Subscribers
|
Fintech companies register to participate in the Peer-to-Peer Lending Trial Mechanism
|
|
3
|
How to apply
|
Fintech companies can register in one of two ways:
- Submit your application via postal service.
- Submit directly to the One-Stop Shop of the State Bank of Vietnam.
|
|
4
|
Components of the dossier
|
Fintech companies wishing to register for a trial of peer-to-peer lending solutions shall send 02 sets of dossiers, including:
- Application form No. 03, Appendix I attached to Decree 94/2025/ND-CP.
- Documents describing the organizational structure, management and administration when implementing peer-to-peer lending solutions registered to participate in the Pilot Mechanism.
- Resolutions of the Board of Members, the Board of Directors, the General Meeting of Shareholders, and documents of the owner's competent representative in accordance with the competence specified in the Charter on the adoption of the Scheme describing peer-to-peer lending solutions for registration to participate in the Trial Mechanism.
- The scheme describing peer-to-peer lending solutions registered for participation in the Pilot Mechanism is specifically guided in Appendix III attached to Decree 94/2025/ND-CP.
- The trial plan, including: Time, space and expected scope of testing, estimated funding for testing activities, expected resources to participate in testing and principles of exchange and reporting to the State Bank during the testing period; The termination of testing ensures the feasibility of fulfilling obligations to customers and stakeholders after the decision to stop testing.
- Personnel dossiers include curriculum vitae, judicial record card (no more than 06 months before the time of submission of the dossier), copies of diplomas proving the professional capacity and qualifications of the legal representative, General Director (Director); a document of the competent representative of the unit where the legal representative, the General Director (Director) has been or is working to certify the position and time of holding the position or a copy of the document proving the position and time of holding the position at the unit.
- Copies of documents proving that the Fintech Company is legally established and operating, including: Establishment License or equivalent papers, Charter.
- Enclosed with 06 CDs (or 06 USBs) storing scanned copies of the complete dossier requesting the issuance of the Certificate of participation in the Testing Mechanism
|
|
5
|
Results
|
Certificate of Participation in the Testing Mechanism
|
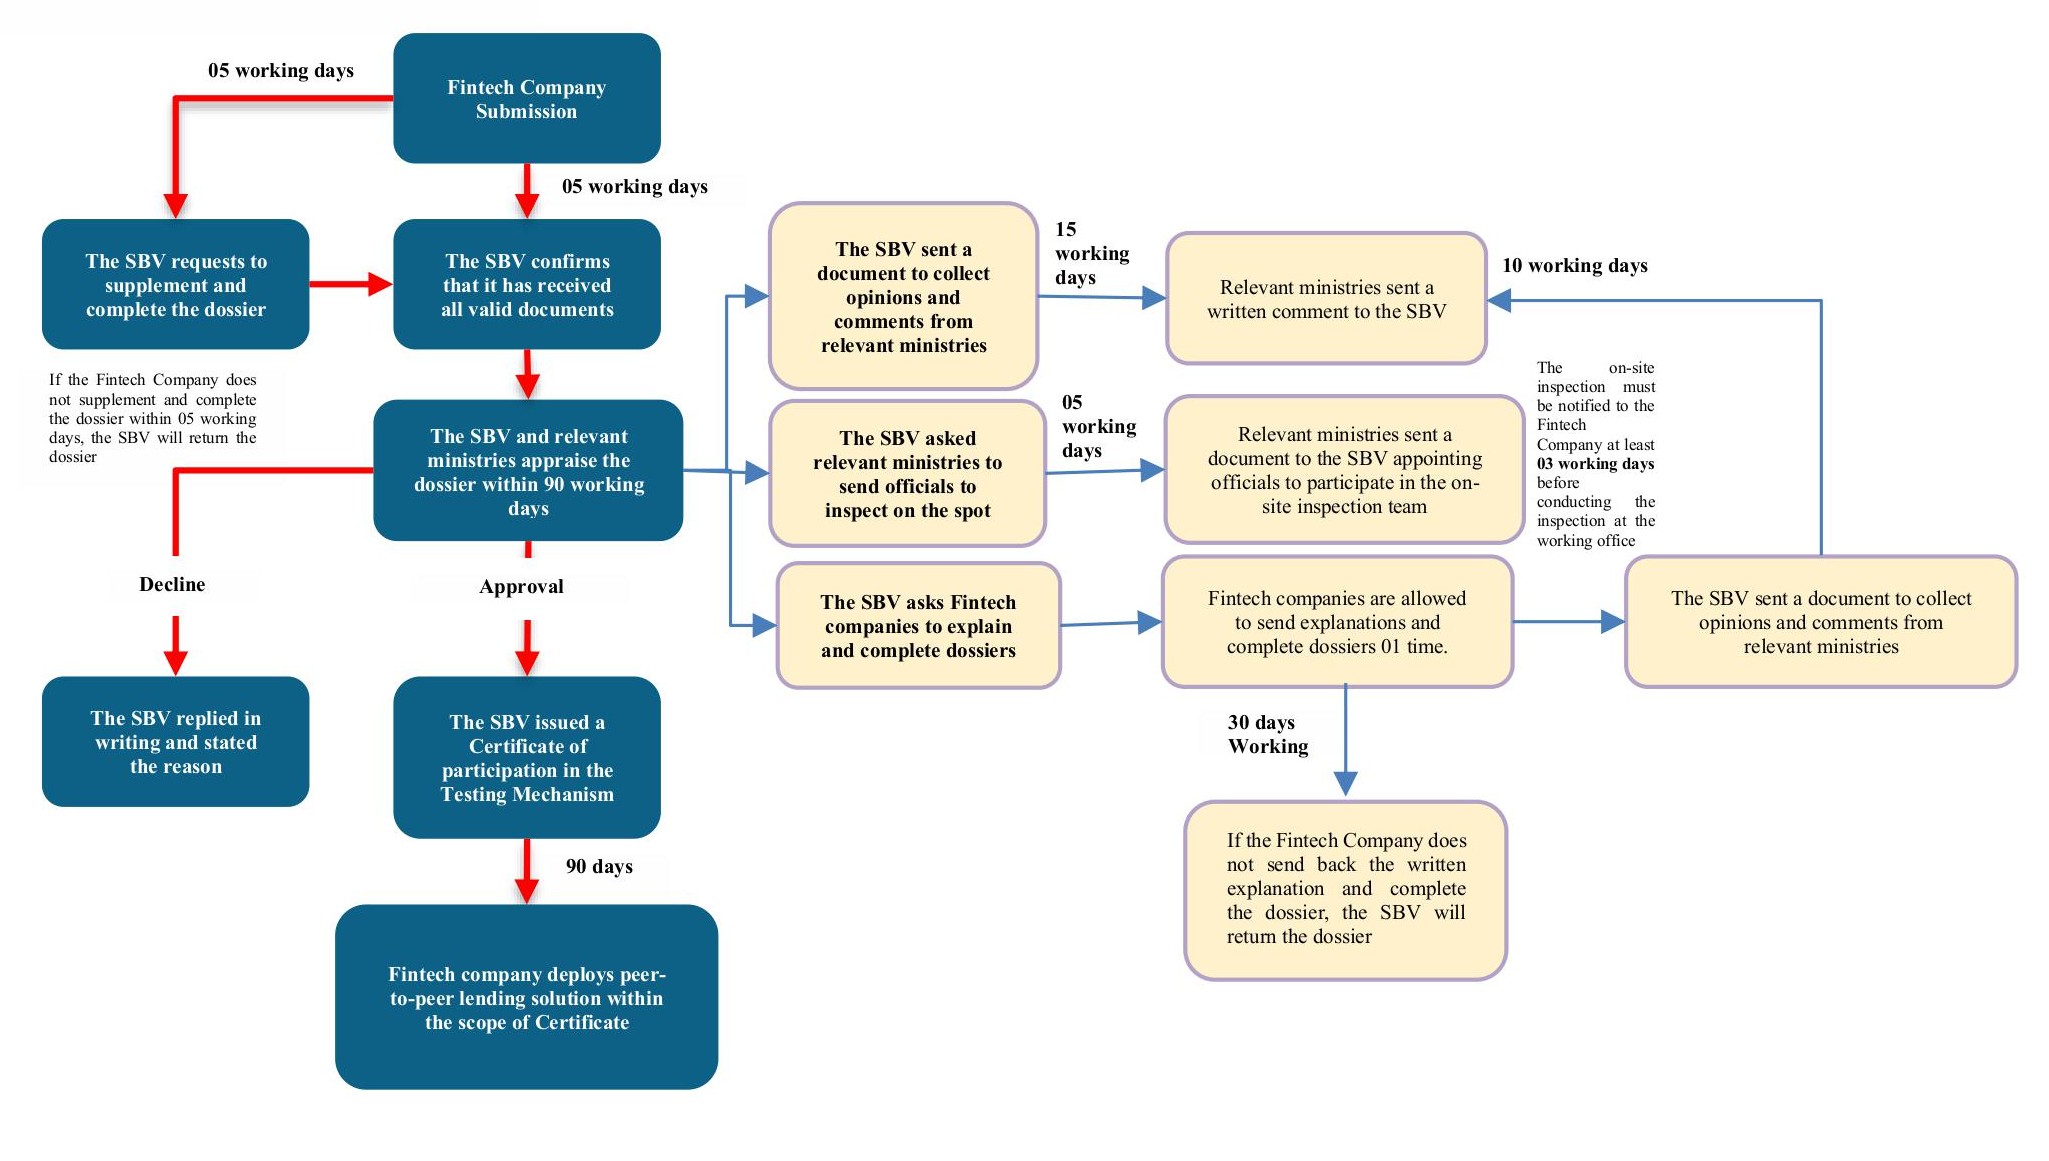
4. Order of procedures for registration to participate in the Peer-to-Peer Lending Trial Mechanism
[1] Article 13 of Decree 94/2025/ND-CP


