


Foreign workers working in Vietnam are foreign individuals who are obliged to pay and register taxes directly with tax authorities. These individuals are considered to have incomes subject to personal income tax[1] or other individuals who have obligations to the state budget[2]. Tax registration can be carried out through the following two forms: (1) foreign workers directly carry out tax registration; (2) The foreign worker through the income-paying agency/unit and authorizes this agency/unit to carry out tax registration.
1. Overview of tax identification number procedures for foreign workers in Vietnam
|
STT |
Category |
Content |
|
|
1 |
Object |
Foreign workers through income-paying agencies and authorize income-paying agencies to register tax for foreign workers or dependents.[3] |
The foreign worker does not go through the income-paying agency and does not authorize the income-paying agency to register tax for the foreign worker or his or her dependents.[4] |
|
2 |
Application location |
At the income-paying agency.
Note: In case a foreign worker pays income tax at multiple income-paying agencies in the same tax payment period, the foreign worker shall only authorize tax registration at one income-paying agency and notify the foreign worker's identification number of the foreign worker and his or her dependents to the agencies pay other incomes for use in tax deduction, declaration and payment.
|
|
|
3 |
Components of the application |
The dossier comprises:[5]
|
The dossier comprises:[6] For foreign employees with taxable income:
For dependents: |
|
4 |
Responsibilities of the paying agency |
The income-paying agency shall:[7] |
Foreign workers do it themselves |
|
5 |
Fees |
There is no fee. |
|
|
6 |
Result |
Case: Complete dossier as prescribed The tax officer shall receive and process the tax registration for the first time and notify the tax identification number of the foreign worker. Case: The dossier is incomplete as prescribed
|
|
2. Order and procedures for granting tax identification numbers to foreign workers in Vietnam
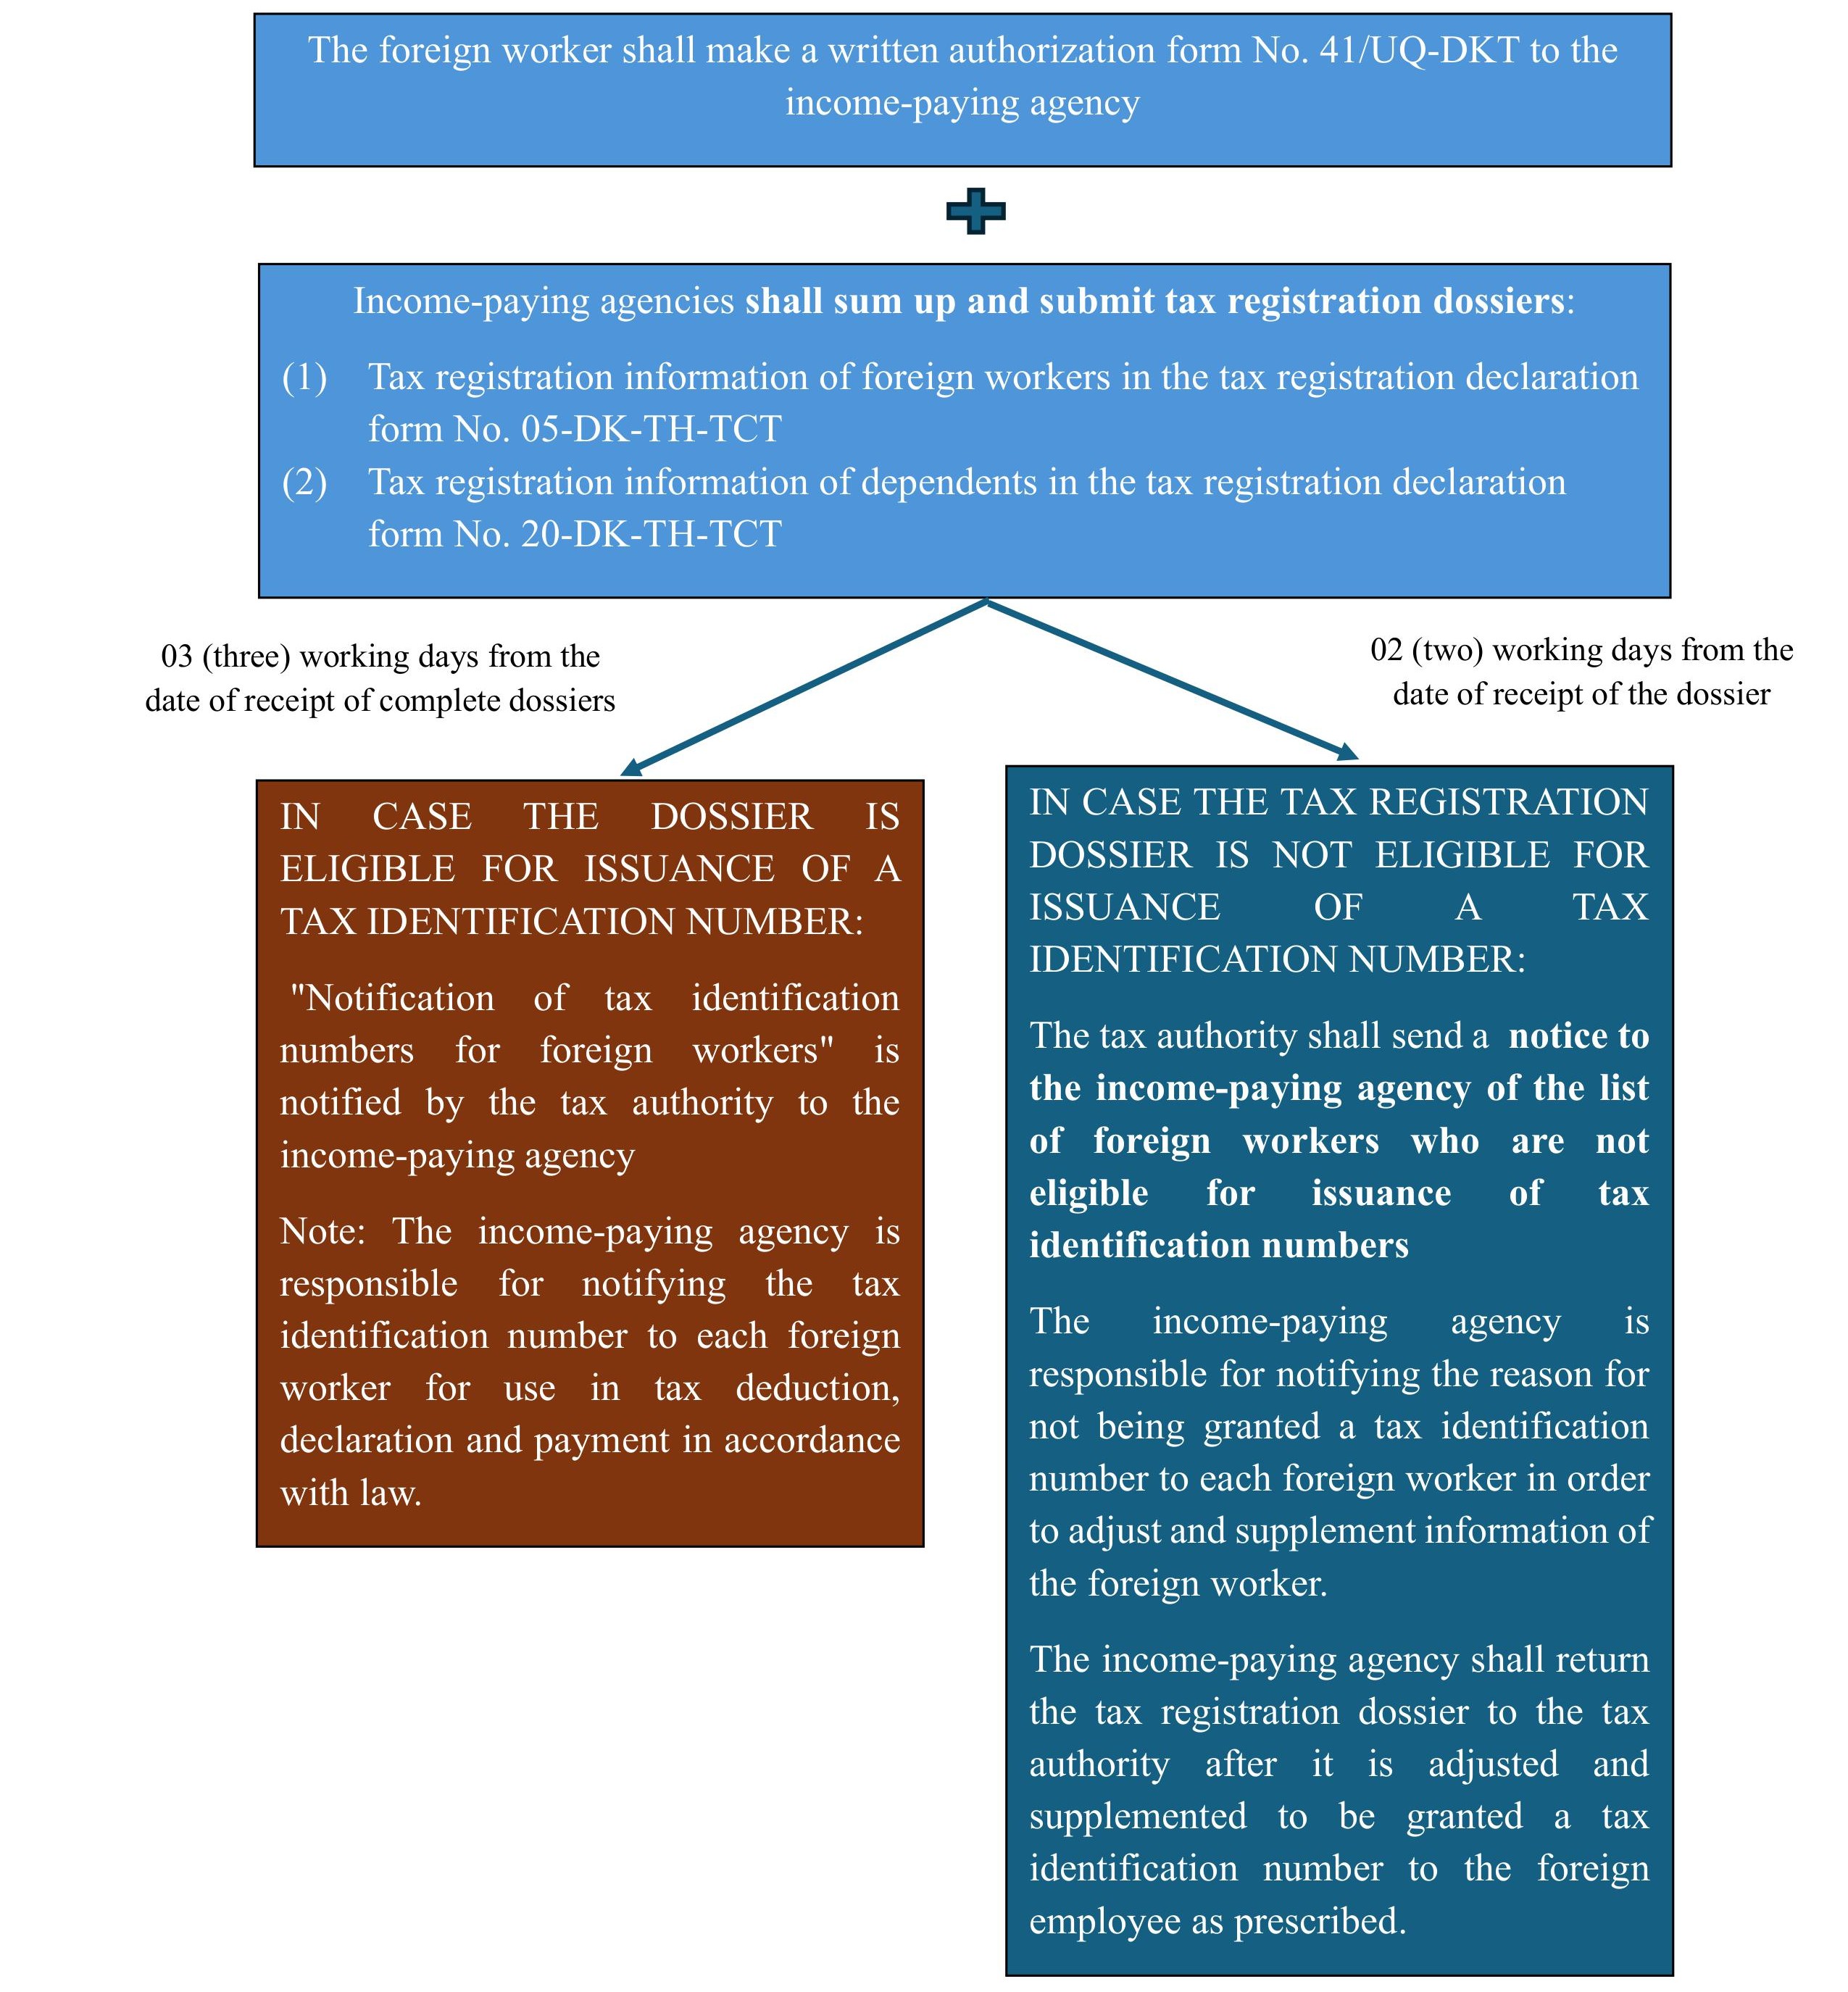
Case 1: The foreign worker through the income-paying agency and authorizes the income-paying agency to register tax for the foreign worker or his or her dependents.
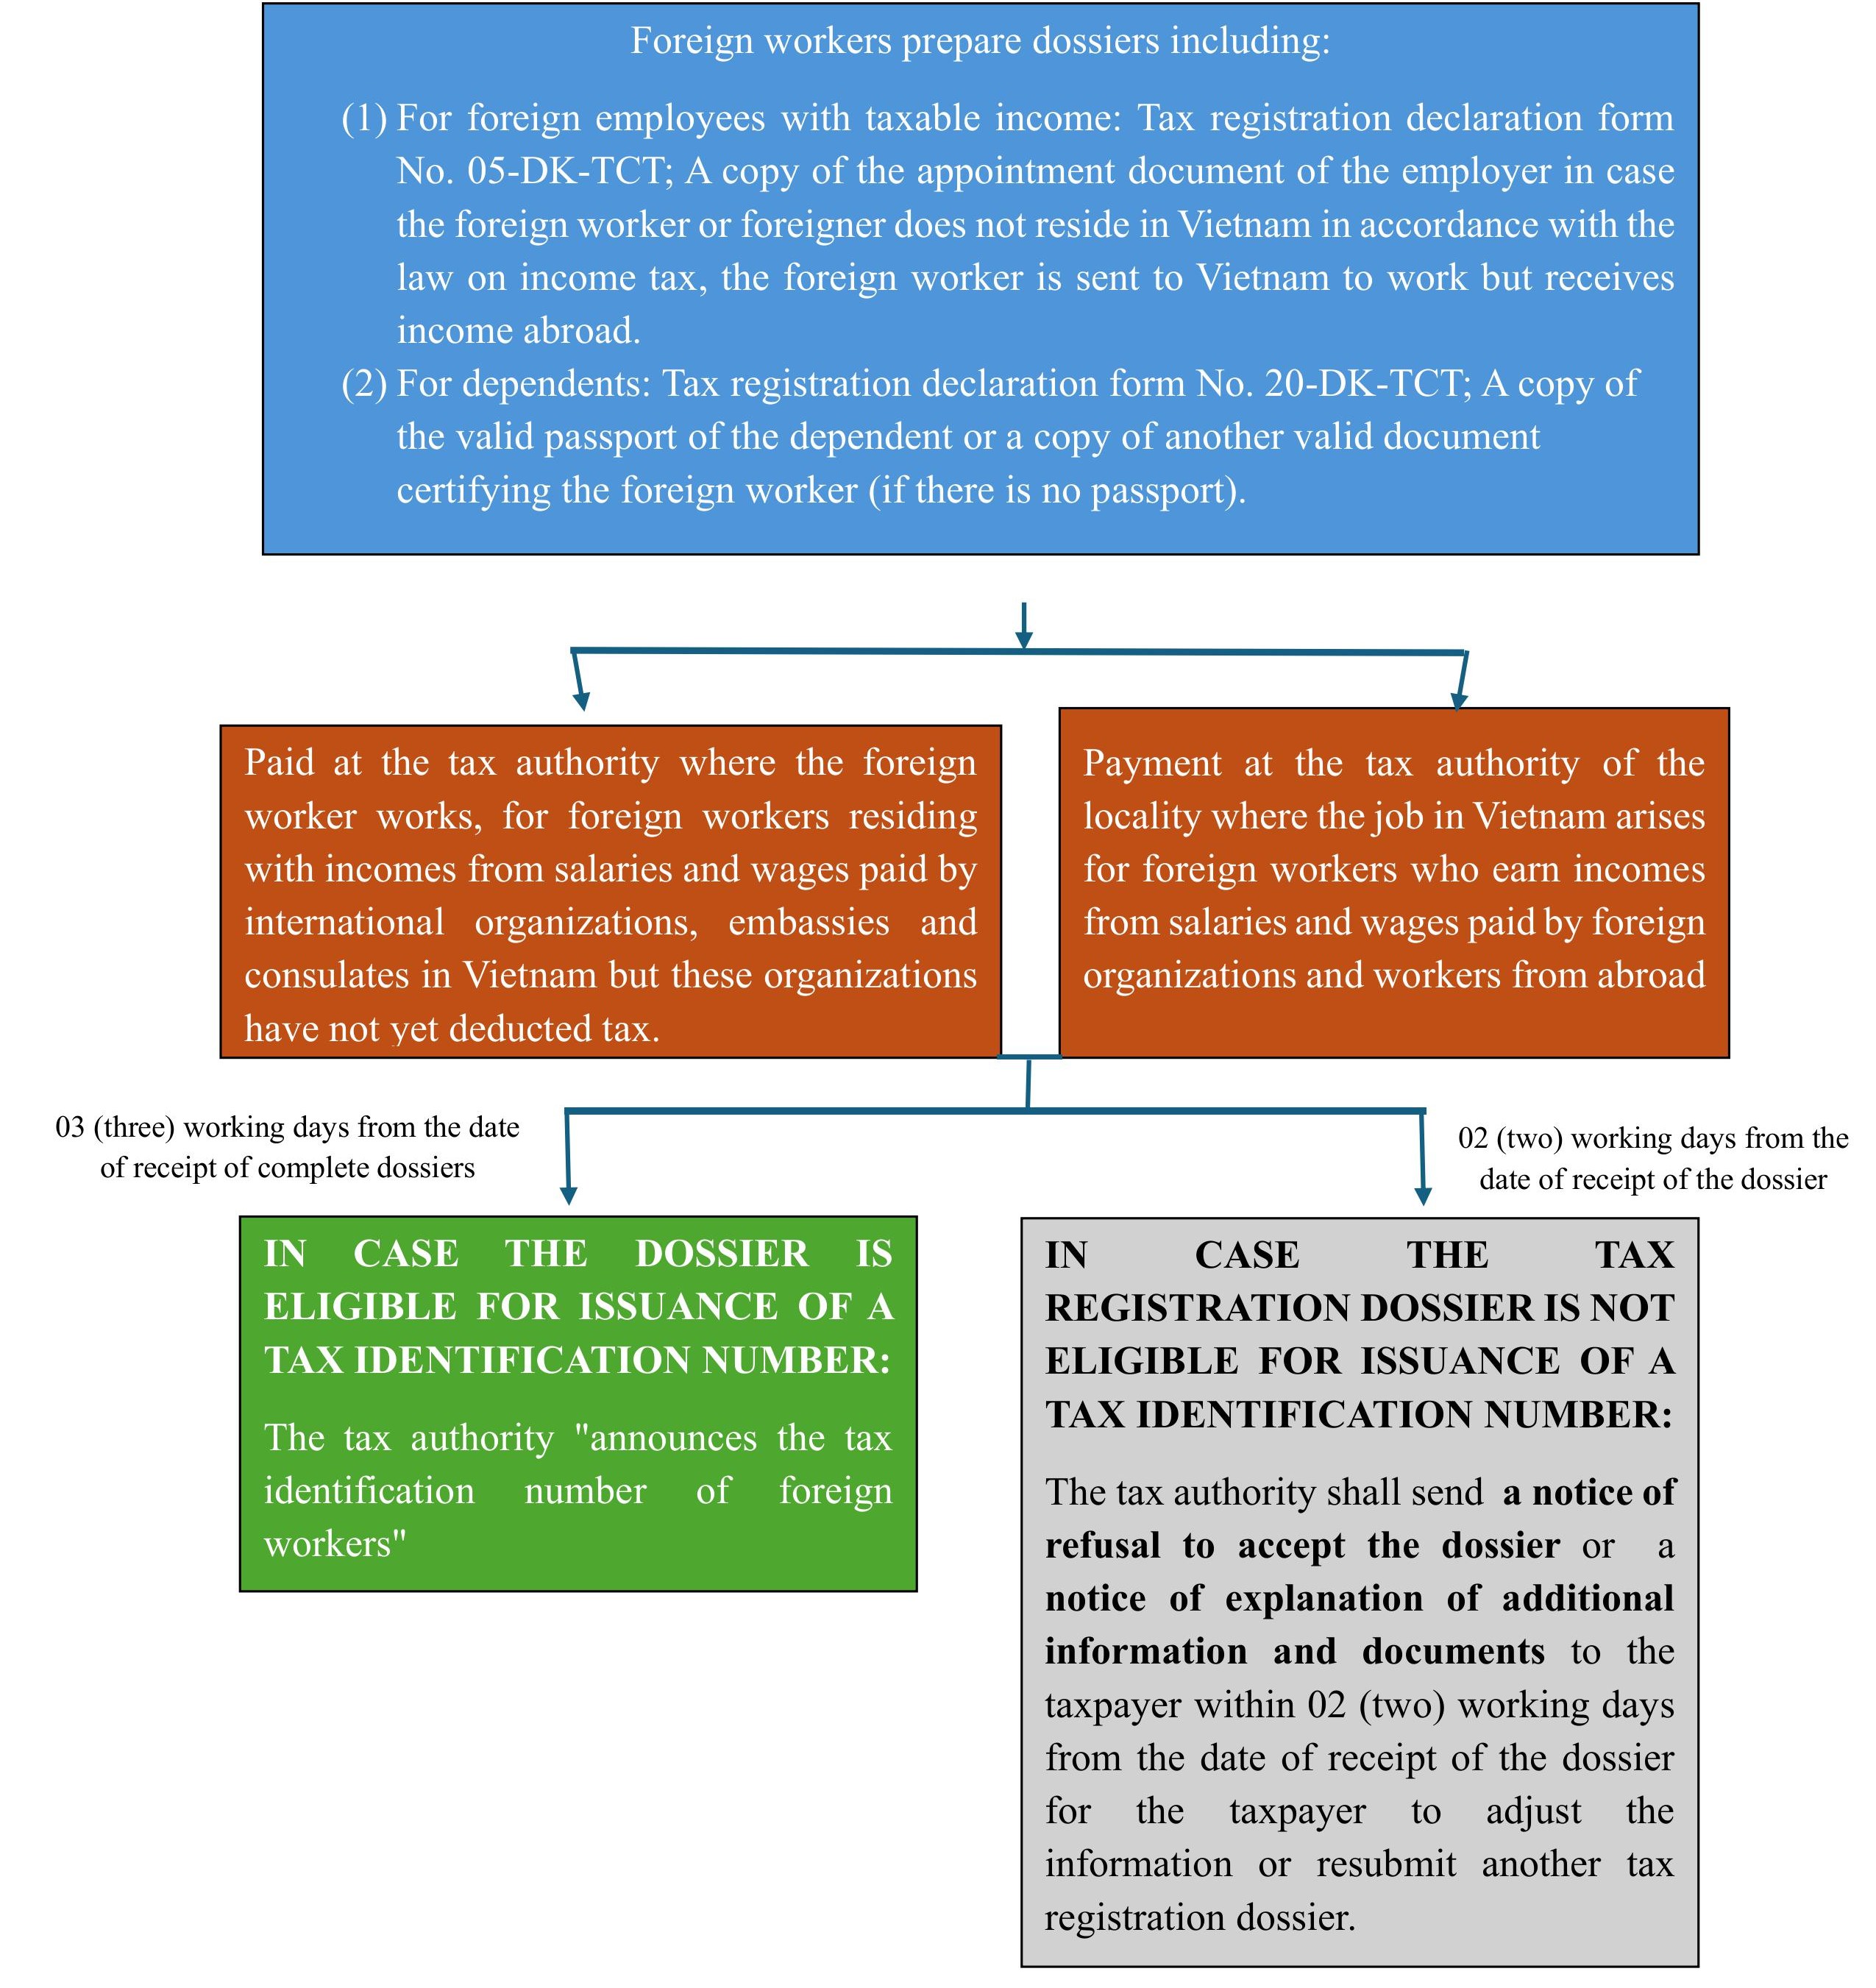
 Case 2: The foreign worker does not go through the income-paying agency and does not authorize the income-paying agency to register tax.
[1] Point k, Clause 2, Article 4 of Circular 86/2024/TT-BTC.
[2] Point n, Clause 2, Article 4 of Circular 86/2024/TT-BTC.
[3] Point b, Clause 2, Article 22 of Circular 86/2024/TT-BTC.
[4] Point c, Clause 2, Article 22 of Circular 86/2024/TT-BTC.
[5] Sections b2, b3, Point b, Clause 2, Article 22 of Circular 86/2024/TT-BTC.
[6] Section c3, Point c, Clause 2, Article 22 of Circular 86/2024/TT-BTC.
[7] Section b3, Point b, Clause 2, Article 22 of Circular 86/2024/TT-BTC.
[8] Point a, Clause 2, Article 6 of Circular 86/2024/TT-BTC.
[9] Point a, Clause 2, Article 6 of Circular 86/2024/TT-BTC.
[10] Point b, Clause 2, Article 6 of Circular 86/2024/TT-BTC.


