


Today, insurance products are considered an integral part of the lives of individuals and organizations, playing a role in supporting both individuals and organizations in reducing risks and financial stability. Along with the increase in demand and the emergence of complex and potentially risky transactions, the completion of relevant legal regulations is considered one of the top priorities.
Manulife Vietnam recorded a profit of VND 1,699 billion and paid out nearly VND 4,000 billion in insurance benefits in the first half of 2024. Source: VnEconomy
Recently, a new step has been opened with the legal framework in the field of insurance business in Vietnam when the Law Amending and Supplementing a Number of Articles of the Law on Insurance Business 2025 has been passed, and takes effect from January 1, 2026. Accordingly, new standards are completely established, aiming to create a sustainable and transparent environment.
1. Duration of compulsory official operation for insurance enterprises
Compared to the old regulations, although the amended Law on Life Insurance does not change the 12-month term, there is a stricter control when considering the entire process before official operation. Accordingly, the enterprise must fulfill the obligation to complete the mandatory contents, including:[1] (i) fully pay the charter capital or the allocated capital; (ii) electing and appointing legal representatives; to elect and appoint positions approved by the Ministry of Finance; (iii) building organizational and management structures, internal control systems, and internal audits; (iv) promulgating processes and regulations in accordance with law; (v) make a full deposit at a commercial bank operating in Vietnam. The mechanism sets out basic requirements to ensure that insurance businesses operate in a transparent manner and in accordance with their operations in the Vietnamese market.
In addition, at the same time, exceptions are set in case of force majeure events or objective obstacles, resulting in the enterprise not being able to operate officially within the prescribed time. However, in this case, the enterprise needs to report in the form of a written report and must have written approval from the Ministry of Finance to extend the time of operation.[2] The time for the extension is up to 12 months and can only be extended once.
2. Raising the conditions and standards of managers and controllers of insurance enterprises
Regulations on conditions and standards for managers of insurance enterprises have been amended more comprehensively, especially related to groups of general conditions. In Clause 5, Article 1 of the amended Law on Insurance Policy, individual managers must simultaneously meet the following 03 criteria:
Firstly, this subject is not sanctioned for administrative violations in the field of insurance business. This is an important initial condition to avoid cases of continued violations during the operation of the insurance enterprise, limit risks for the insurance enterprise itself and other related parties such as customers, businesses wishing to buy insurance,...
Secondly, for a period of 03 consecutive years before the time of appointment, this individual has not been disciplined in the form of dismissal due to violation of internal procedures.
Finally, it is not a case of being prosecuted by a competent authority at the time of being elected or appointed.
In previous drafts, this group of general conditions has been abolished according to the policy in Resolution No. 198/2025/QH15 on reducing and simplifying business investment conditions for enterprises, removing difficulties and obstacles of enterprises in terms of human resources.[3] However, the new regulation continues to add back to these requirements when considering necessity. Because, individual managers need to ensure not only their capacity but also their qualifications and ethics when they are the ones who directly operate, have the authority to control and make all decisions of the business.
In addition to the general conditions, the amended Law on Insurance continues to inherit and guide the regulations on conditions and standards of each top position at the insurance enterprise in Article 81. Accordingly, Article 24 of the Draft Decree[4] specifically guides the order, procedures and dossiers when the enterprise has a decision to appoint or replace leading positions such as the Chairman of the Board of Directors, the Chairman of the Board of Members, the General Director (Director).
3. Individuals acting as insurance agents are only allowed to act as agents for an enterprise of the same type
Currently, the scope of operation of insurance agents in the new regulations has been clarified the previous problems of enterprises. Specifically, if an individual has acted as an insurance agent for one party, he or she cannot simultaneously act as an agent for another insurance business party of the same type.[5] For example, if Individual A acts as a life insurance agent for Party B and Party C also deals in life insurance, Individual A cannot act as an agent for Insurance Company C.
In terms of legislation, the above regulation shows that the lawmaker has anticipated and prevented the risk of unfair competition in insurance business activities, especially in the context of the increasingly developed and diversified insurance market. In fact, an agent representing many insurance enterprises of the same type at the same time is very likely to be biased, prioritize the product offering of a certain enterprise, or cause confusion to the insurance buyer about the representation, related rights and obligations. This not only affects the interests of customers but also negatively affects the competitive environment among insurance businesses.
In addition, the amended Law on Insurance does not set absolute restrictions on the diversification of insurance agency activities. Accordingly, individuals can still simultaneously act as insurance agents for many different businesses if these businesses do not do the same type of insurance. For example, individual A may act as a life insurance agent for enterprise B, and at the same time act as a non-life insurance or health insurance agent for enterprise C on the condition that it fully meets the standards and conditions for practice as prescribed by law.
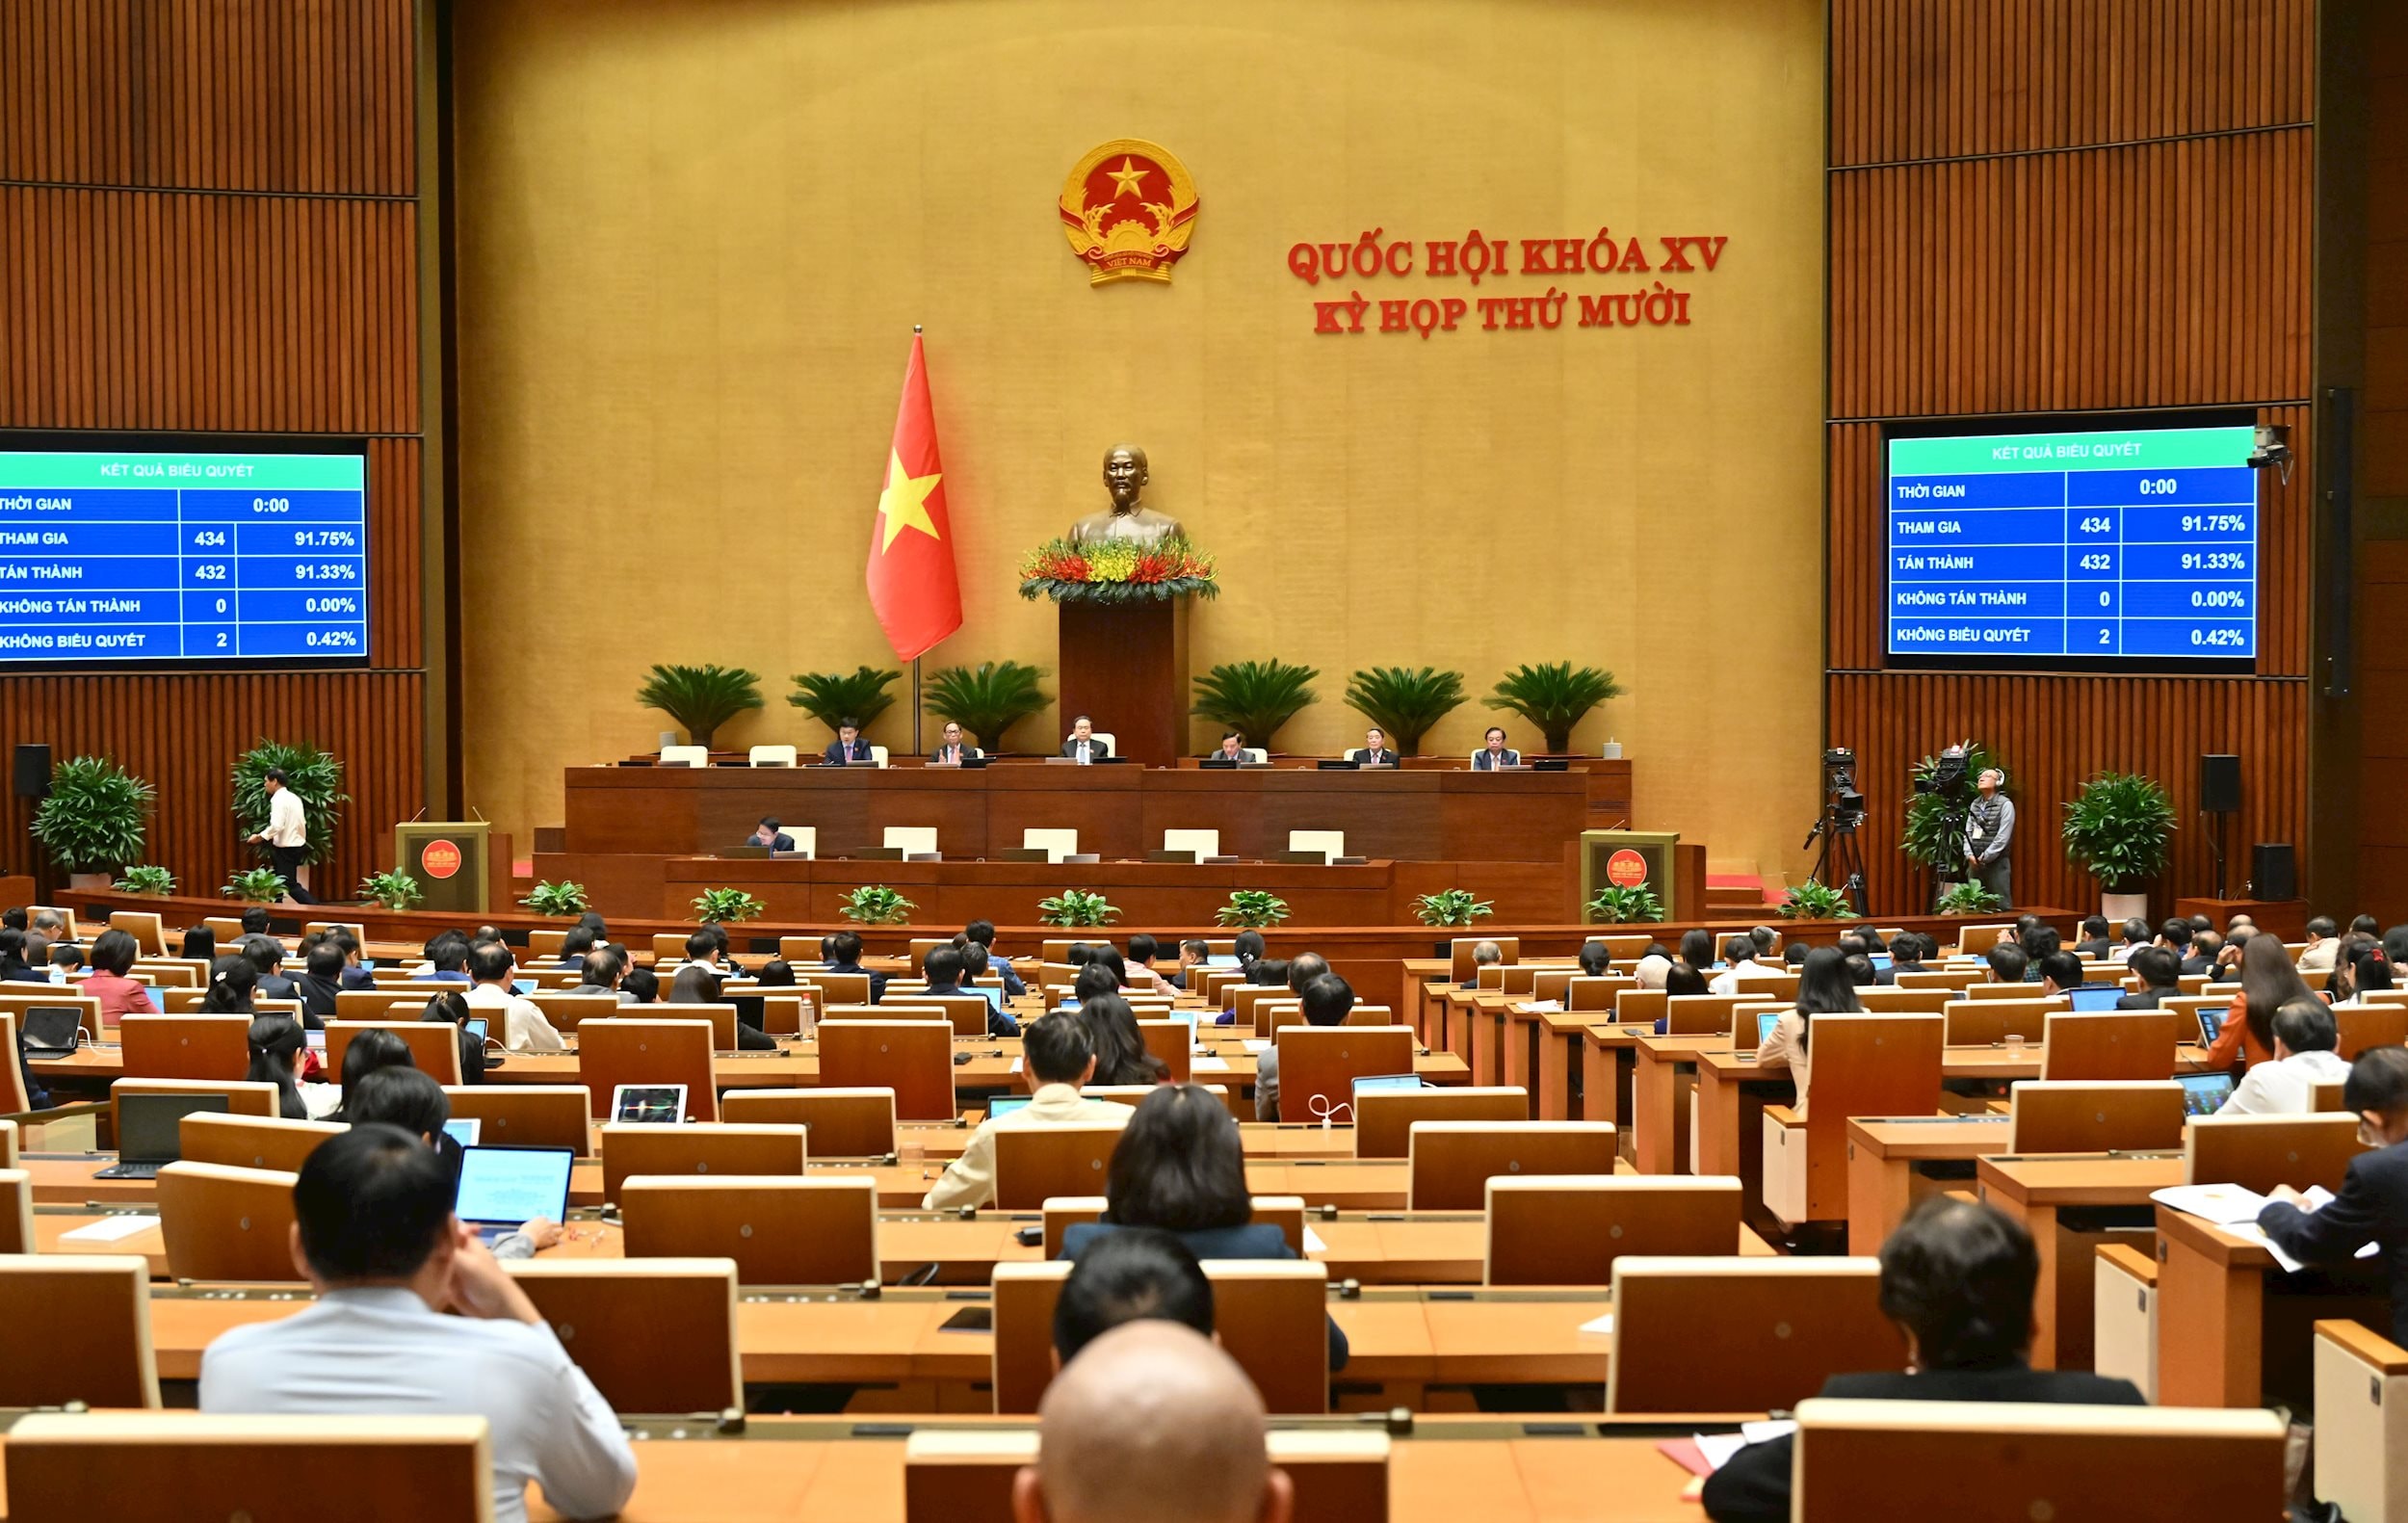
The National Assembly voted to pass the Law amending and supplementing a number of articles of the Law on Insurance Business with 432 out of 434 attending deputies voting in favor, reaching 99.53%. Source: National Assembly Office
4. Detailed regulations on separation of equity and premium sources
Previously, enterprises in the field of insurance were required to register in principle with the Ministry of Finance and separately separate, record and monitor the source of equity and insurance premiums. However, new regulations on this issue are tending to simplify in terms of administrative procedures.[6] Non-life insurance enterprises and branches of foreign insurance enterprises only need to notify in writing in principle before implementation. From there, the Ministry of Finance will save, monitor and strengthen post-inspection supervision. The reason for this regulation comes from the special nature of non-life insurance when this is a short-term financial product, often transferred to reinsurance, leading to this cash flow not being kept in the business for a long time and not long-term accumulation for the business.[7] Therefore, it is not necessary to tighten administrative procedures such as registration. On the contrary, only in the case of long-term products such as life insurance, it is necessary to register and implement the method approved by the Ministry of Finance.
Prior to the above change, the latest Draft Guiding Decree has eliminated the obligation to register the above subjects and added the obligation to notify instead, and at the same time, added the phrase "notification" in the regulations on dossiers and procedures.[8] Accordingly, the registration, notification or change of registration will be carried out within 30 days from the date of receipt of a complete dossier, including: (i) a written request for registration, notification or change according to the form in Appendix XI issued together with the Decree; (ii) Explanatory documents on the principles of separation and allocation expected to be applied on the basis of certification of actuaries of enterprises and branches; (iii) a document explaining the change (in case the change is made).
5. Limiting investment activities of insurance brokerage businesses from 2026
In order to ensure that the investment activities of insurance brokerage enterprises are carried out safely, transparently and effectively, the amended Law on Insurance has added regulations limiting the form of investment of this group of enterprises. Accordingly, insurance brokerage enterprises are not allowed to make investment in the form of loans or capital grants to shareholders, capital contributors or related persons of shareholders and capital contributors in accordance with the provisions of the Law on Enterprises, except for the case of depositing money at shareholders. members being credit institutions.
The above exception was approved on the basis of the safety and low risk of deposits at banks, and at the same time ensuring high liquidity and cash flow control of the enterprise. In this context, allowing SMEs to deposit money at shareholders and members who are credit institutions does not give rise to significant risks to the equity of the enterprise, but also contributes to preserving capital sources and maintaining financial stability.
Before the amended Law on Insurance Business took effect, the Law on Insurance Business 2022 and its guiding documents did not have specific regulations on investment activities for insurance brokerage enterprises. This legal gap has led to the fact that these enterprises can carry out risky investment activities, especially internal investment or provide capital to entities with ownership and management relationships, making it difficult to supervise. control the management and use of equity. This has the potential to negatively affect the financial situation, solvency as well as the sustainability of the operation of the insurance brokerage business.
In general, the new provisions of the law on insurance business are set in the direction of stricter conditions, standards, and decentralization mechanisms, and at the same time promote autonomy in insurance business activities. The change helps increase the efficiency of state management and motivates businesses to optimize costs and improve competitiveness. The orientation of shifting from the "pre-inspection" to "post-inspection" model with a focus on risk management and compliance with international standards is expected to improve financial safety, attract investment and improve the quality of Vietnam's insurance market in the coming time.
Nguyen Viet Hung
HM&P Law Firm
Read more: Luật Kinh doanh bảo hiểm sửa đổi: Đặt ra những tiêu chuẩn mới cần thiết cho một thị trường minh bạch
[1] Clause 3, Article 1 of the Law Amending and Supplementing a Number of Articles of the Law on Insurance Business 2025.
[2] Clause 3, Article 1 of the Law Amending and Supplementing a Number of Articles of the Law on Insurance Business 2025.
[3] Ministry of Finance. (2025). Comparison table of the Law on Insurance Business in 2022 and the Law Amending and Supplementing a Number of Articles of the Law on Insurance Business. pp. 12-13.
[4] Article 24 of the Draft Decree amending and supplementing a number of articles of the Government's Decree No. 46/2023/ND-CP dated July 1, 2023 detailing the implementation of a number of articles of the Law on Insurance Business.
[5] Clause 3, Article 1 of the Law Amending and Supplementing a Number of Articles of the Law on Insurance Business 2025.
[6] Clause 8, Article 1 of the Law Amending and Supplementing a Number of Articles of the Law on Insurance Business 2025.
[7] Ministry of Finance. (2025). Comparison table of the Law on Insurance Business in 2022 and the Law Amending and Supplementing a Number of Articles of the Law on Insurance Business. p. 21.
[8] Article 51 of the Draft Decree amending and supplementing a number of articles of the Government's Decree No. 46/2023/ND-CP dated July 1, 2023 detailing the implementation of a number of articles of the Law on Insurance Business.


