


This article was written by our Managing Partner Nguyen Van Phuc and Lawyer Nguyen Nhat Duong published in the Legal Electronic Magazine on December 14, 2023. At the same time, the remarks by Managing Lawyer Nguyễn Văn Phúc were also featured in The Saigon Times on May 11, 2024. Below is the English version:
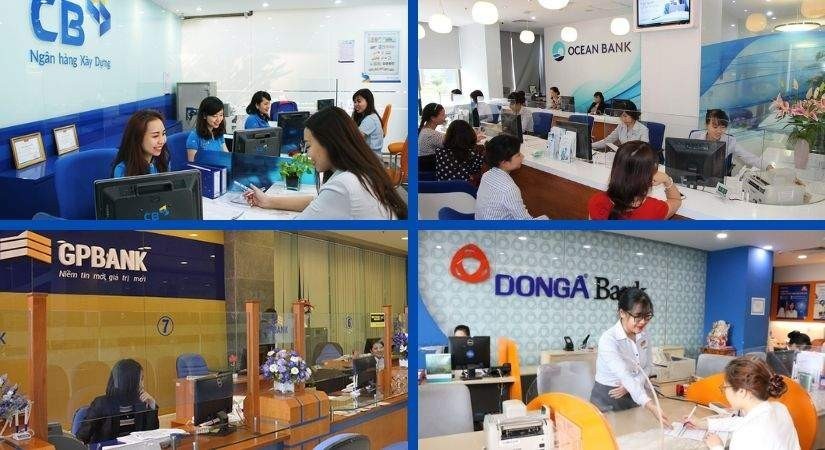
In 2015, in the face of serious and difficult-to-cure violations by weak commercial banks, the State Bank decided to take over three banks, namely Construction Bank ("CB Bank"), Ocean Commercial One Member Limited Liability Bank ("OceanBank"), and Global Petro Sole Member Limited Commercial Bank ("GP Bank"), at a price of 0 VND. However, the restructuring of these commercial banks proved to be ineffective in practice, as their businesses continued to incur losses, faced difficulties in recovering bad debts, and even faced the risk of dissolution or bankruptcy.
In view of the practical challenges faced by the aforementioned banks, the Law on Credit Institutions 2010, as amended in 2017, added the mandatory transfer option as one of the specific restructuring measures for controlled credit institutions. This option is considered crucial, but also complex, as it requires strict compliance with legal regulations. In this article, we will address some prominent legal issues related to the mandatory transfer of banks under the Law on Credit Institutions 2010, as amended and supplemented in 2017 ("Law on Credit Institutions").
1. What is a mandatory bank transfer?
Pursuant to the provisions of the Law on Credit Institutions, a compulsory transfer is a measure by which the owner, capital contributor or shareholder of a specially controlled commercial bank is obliged to transfer the entire shares or capital contribution to the transferee. The transferee may be a domestic credit institution, a foreign credit institution or another eligible investor proposed and approved by the competent state authority to receive the mandatory transfer.
Sources: Legal Electronic Magazine
This option is considered a "revitalization" opportunity for specially controlled banks, but it also imposes a burden on the transferee. At present, the State Bank is accelerating the compulsory transfer process for the three banks acquired at 0 VND, namely CB Bank, OceanBank and GP Bank, as well as Dong A Commercial Joint Stock Bank ("DongA Bank"), another specially controlled bank. To date, the actual transfer process has not started due to difficulties in identifying and negotiating with eligible commercial banks (financial capacity, management, experience in restructuring weak credit institutions), which heavily relies on the voluntary participation of commercial banks. In addition, the transferee also needs considerable time to convince shareholders, especially large and strategic foreign shareholders, to unanimously participate in the mandatory transfer.
2. Conditions and rights of the parties in a mandatory transfer relationship
According to the Law on Credit Institutions, the parties involved in the mandatory transfer activities include the transferred bank and the transferor.
According to the current legislation, the transferred bank is a bank that is considered to be weak, subject to special supervision and falls into one of the following cases:
(i). Is or may become insolvent or insolvent as defined by the regulations of the State Bank.
(ii). Accumulated losses in excess of 50% of its charter capital and reserves as shown in its most recent audited financial statements.
(iii). Failing to maintain the prescribed capital adequacy ratio under Point b Clause 1 of Article 130 of the Law on Credit Institutions for 12 consecutive months or having a capital adequacy ratio of less than 4% for 06 consecutive months.
(iv). Receives a weak rating under the regulations of the State Bank for 02 consecutive years.
Meanwhile, the transferee is a qualified entity based on the decision of the State Bank and includes two categories:
(i). Domestic and foreign credit institutions.
(ii). Other investors.
For credit institutions, the transferee must meet conditions such as profitable operations for at least 02 consecutive years, compliance with the safety ratios for credit institutions according to the laws, and sufficient capital to contribute according to the approved mandatory transfer plan. Non-credit institution investors, while exempt from the safety ratio requirements, must still comply with the business operation and capital source requirements for the mandatory transfer plan. Importantly, individual participation in the mandatory transfer is not allowed to ensure that the transferee has strong financial capacity and professional management experience. This is to ensure that the weak credit institution continues its stable operations and avoids the risk of bankruptcy after the transfer.
Although the conditions for mandatory transfer are strict, the transferee enjoys significant rights. The current Law on Credit Institutions provides for numerous rights of the mandatory transferee, including:
- Owning 100% of the charter capital if the commercial bank is transformed into a single-member limited liability bank by mandatory transfer.
- Not to consolidate the financial statements of the transferred commercial bank.
- Exclusion from the caculation of the capital adequacy ratio calculation for the transferred commercial bank.
- Exemption of capital contributions to the transferred commercial bank from the provisions on the establishment of reserves for the impairment of investments and from the calculation of the capital adequacy ratio in the event of a capital contribution or purchase of shares in the credit institution receiving the transfer.
The capital contribution or purchase of shares in the credit institution receiving the transfer is carried out on the basis of the ratios specified in the approved mandatory transfer plan.
- Sale or issue of shares of the receiving credit institution to foreign investors in accordance with the approved mandatory transfer plan.
- Application of one or more reorganization support measures in accordance with the Law on Credit Institutions and the approved mandatory transfer plan.
Meanwhile, the transferee, which is not a credit institution, has the right to exceed the ownership limit established by the Law on Credit Institutions for shares and contributed capital of the transferred commercial bank.
It is obvious that the rights of the mandatory transferee in participating in the mandatory transfer are substantial.
Conversely, for the transferred commercial bank, all rights and interests of the owner, capital contributor or shareholder of the transferred commercial bank cease from the moment when the State Bank makes a decision on the mandatory transfer. The transferee shall assume and be responsible for all rights and obligations of the transferred commercial bank, including customer deposits and loans.
3. Increasing the share of foreign investors in the capital of the acquiring credit institution
In addition to the aforementioned rights, domestic credit institutions that engage in mandatory transfer activities may further benefit from the proposed amendments concerning the increase of capital ownership by foreign investors. Recently, the State Bank submitted a proposal to the Government to issue a decree amending and supplementing Decree No. 01/2014/NĐ-CP of January 03, 2014 on foreign investors acquiring shares in Vietnamese credit institutions. The noteworthy proposal proposes to increase the total ownership limit of foreign investors in the transferee to more than 30%, but not more than 49% of the charter capital of the mandatorily transferred bank (excluding commercial banks where the State holds more than 50% of the charter capital). By supplementing the financial resources and management experience of foreign partners, the management and operation of the transferee is expected to be more advantageous for the transferred bank.
4. Other legal issues
Sources: https://www.cbbank.vn/
In addition to the specific legal issues set forth in the Law on Credit Institutions and related implementing documents, mandatory transfer activities may give rise to various legal concerns that need to be carefully considered by all parties. For example, the regulations on economic concentration procedures currently include such forms as (i) mergers of enterprises; (ii) consolidations of enterprises; (iii) acquisitions of enterprises; (iv) joint ventures between enterprises; and (vi) other forms of economic concentration as provided by law. Although the mandatory transfer involves the transfer of all shares and contributed capital from the owner, contributing member or shareholder of the transferred bank to the transferee, it remains unclear whether this could be considered a business acquisition. The Law on Credit Institutions itself also outlines the possibility of transferring all shares and contributed capital of a specially controlled bank. If the mandatory transfer does not fall under the category of a business acquisition, it requires more specific regulations and guidance, especially from the perspective of competition law. Once the transfer process is completed, it is evident that the size of the transferee, represented by the significantly increased number of banks, will require additional legal procedures. The determination of the transaction as an economic concentration will lead to the emergence of various legal procedures that all parties will have to undertake, such as the notification of the economic concentration (if the thresholds for the notification of the economic concentration are met).
In addition, mandatory transfers may result in significant restructuring of the organizational structure and operations of the transferred bank. In such cases, compliance with labor law issues, in particular with respect to employee termination, becomes a concern for the transferee.
In conclusion, the 2010 Law on Credit Institutions, as amended in 2017, provides a relatively comprehensive legal framework for mandatory transfer activities. However, these activities still face various legal challenges, as discussed above, which require the timely issuance of more specific regulations and guidance by the relevant authorities. At present, mandatory transfer activities are still in the discussion stage, focusing on weak banks, with the cases of CB Bank, OceanBank, GP Bank and DongA Bank being the first applications of this special measure. Therefore, we believe that the mandatory transfer activities for these banks will still require a considerable amount of time to be completed and, in particular, will require prudence and diligence from all relevant parties.
Read more at:
- Legal Electronic Magazine: Hành lang pháp lý cho hoạt động chuyển giao bắt buộc ngân hàng
- The Saigontimes: Cẩn trọng khi chuyển giao bắt buộc ngân hàng yếu kém


